Why China’s Semiconductor Surge Matters: News and Insights
What’s fueling the rapid expansion?
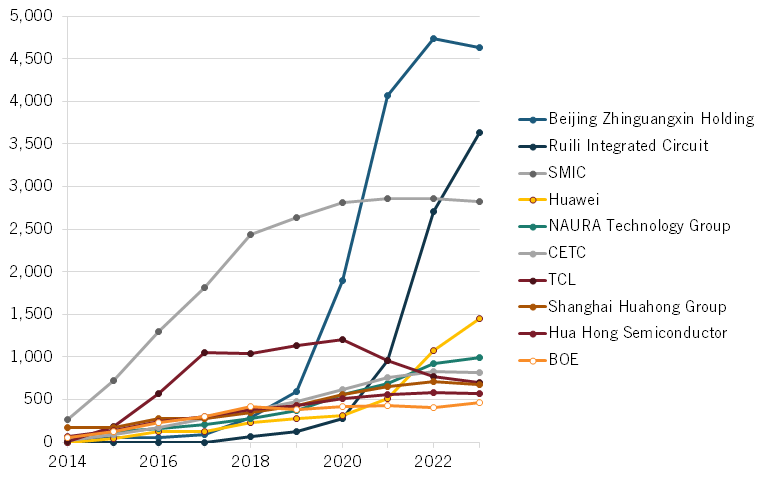
Over the past few years, China’s semiconductor surge has shifted from a buzzword to a tangible force reshaping the global chip landscape. The drive stems from a blend of strategic policy, massive capital inflows, and a determination to close the technology gap with long‑standing leaders such as the United States, South Korea, and Taiwan. While the exact numbers fluctuate, industry observers note a steady climb in domestic wafer fab capacity and a growing portfolio of design firms tackling everything from AI accelerators to 5G radios.
Policy push and state‑backed financing
At the heart of the momentum lies the “Made in China 2025” blueprint, which earmarks semiconductors as a critical sector for self‑reliance. Government ministries have rolled out a cascade of subsidies, tax incentives, and low‑interest loans aimed at both established players and ambitious start‑ups. In practice, this translates into:
- Preferential land‑lease terms for new fab complexes.
- R&D grants that encourage collaboration between universities and private firms.
- Export‑control exemptions that let Chinese designers source advanced equipment from abroad.
These levers together create a fertile ecosystem where a chip design house can secure funding within weeks, a luxury that once required years of venture courting.
Key players emerging on the scene
While giants like SMIC (Semiconductor Manufacturing International Corporation) continue to dominate the foundry segment, a new generation of firms is gaining traction. Companies such as Yangtze Memory Technologies (YMTC) are pushing forward with 3D NAND technologies, while HiSilicon, now operating under a slightly different brand due to export restrictions, still supplies a substantial portion of the processors found in domestic smartphones.
What’s notable is the rise of “fabless” design houses that focus purely on architecture and outsource production to both local and overseas fabs. This model mirrors the success of firms like Qualcomm, but with a distinctly Chinese twist: many of these designers integrate government‑mandated security modules to meet national standards, adding a layer of differentiation that appeals to state‑linked customers.
Global ripple effects and market reactions
International markets have taken note. Analysts often point to a “strategic decoupling” narrative, where foreign chipmakers reassess their exposure to Chinese customers amid tightening export controls. Yet the reality is more nuanced. Some Western equipment suppliers, for instance, have found new revenue streams by licensing older‑generation lithography tools that remain permissible under current regulations.
Meanwhile, supply‑chain observers see China’s surge as a potential buffer against future shortages. By expanding its own fab capacity, the country reduces reliance on a handful of overseas facilities—a factor that could stabilize prices for downstream manufacturers if the trend continues.
Challenges that could slow the ascent
Despite the optimism, several hurdles loom large:
- Technology gap: Advanced nodes below 10 nm still largely depend on equipment from a small set of foreign vendors. Access restrictions keep China a step behind the cutting edge.
- Talent shortage: While engineering programs have swelled, experienced process engineers remain scarce, prompting firms to import expertise from abroad.
- Geopolitical friction: Ongoing trade tensions may trigger sudden policy shifts, threatening the continuity of cross‑border collaborations.
These factors suggest that while China’s semiconductor surge is undeniable, the path to full self‑sufficiency will likely be incremental rather than overnight.
What the surge means for tech enthusiasts
If you follow the latest smartphone releases, you might already be using a chip designed in China, even if the silicon was fabricated elsewhere. For hobbyists, the expanding ecosystem means more affordable development boards and design tools, many of which now come with Chinese‑language documentation and local community support.
On the investment side, the surge has sparked interest in funds that specialize in Asian technology stocks. While the sector remains volatile, many analysts argue that a diversified approach—balancing established players with emerging design firms—offers a way to capture growth without betting on any single technology milestone.
FAQ
Q: Is China now able to produce the most advanced chips (sub‑5 nm)?
A: Not yet. Most sub‑5 nm production still relies on equipment that is tightly controlled by a few overseas companies. China is making progress on slightly older nodes and aims to catch up over the next decade.
Q: How does the surge affect global chip prices?
A: In the short term, increased domestic output can ease pressure on certain commodity segments, such as memory and mid‑range processors. However, high‑end chips continue to command premium prices due to limited supply.
Q: Should consumers expect more Chinese‑branded devices?
A: Likely. As design capabilities improve, Chinese brands are poised to launch devices that compete on both performance and price, especially in markets where cost sensitivity is high.