Invested Capital Turnover: What It Means and Why It Matters
When you glance at a company’s financial statements, you’ll often see ratios that seem to belong in a secret code. One of the less‑talked‑about but surprisingly insightful numbers is invested capital turnover. In plain terms, it measures how efficiently a business converts the money it has tied up in assets into sales. Understanding this metric can reveal hidden strengths—or weaknesses—behind a firm’s profitability.
What Is Invested Capital Turnover?
Invested capital turnover is a efficiency ratio. It answers a simple question: for every dollar of capital that a company has invested in its operations, how many dollars of revenue does it generate?
How It Is Calculated
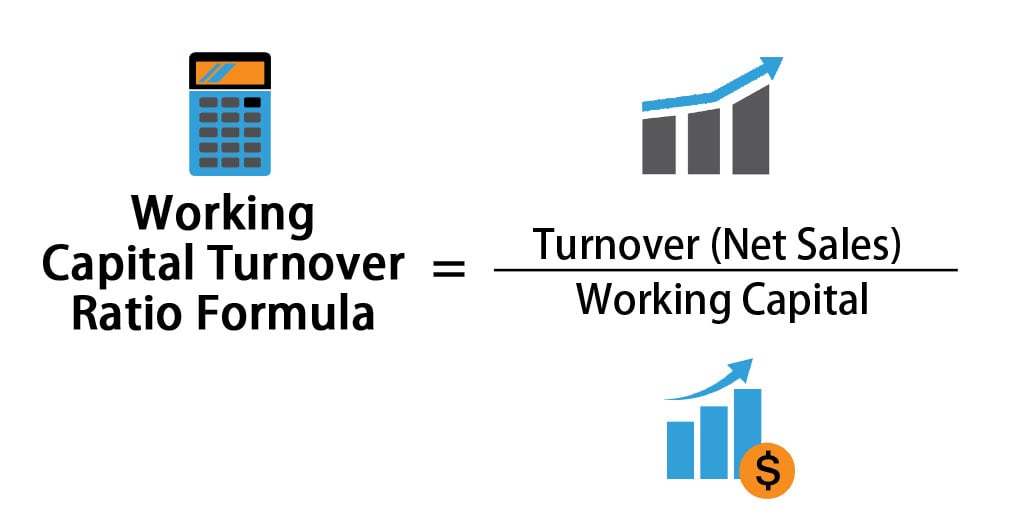
The formula is straightforward:
- Invested Capital Turnover = Net Sales ÷ Average Invested Capital
“Net sales” is the top‑line revenue after discounts and returns. “Average invested capital” is typically the mean of the beginning‑ and ending‑period invested capital balances, which include long‑term debt, equity, and any interest‑bearing liabilities used to finance assets.
Because the ratio uses an average, it smooths out seasonal spikes and provides a clearer picture of ongoing performance.
Why the Ratio Matters
Invested capital turnover sits at the intersection of profitability and asset management. Here are three reasons it deserves a spot on your analyst’s checklist:
- Efficiency Insight – A higher turnover suggests the firm is squeezing more sales out of each dollar of capital, often a sign of strong operational discipline.
- Comparative Power – Unlike raw revenue numbers, the ratio normalizes companies of different sizes, making it easier to compare a boutique manufacturer with a multinational retailer.
- Strategic Flag – When turnover declines, it can hint that new investments aren’t paying off, prompting a deeper dive into capital allocation decisions.
Interpreting Different Levels
There’s no universal “good” number; context matters. In asset‑heavy industries such as utilities or heavy manufacturing, turnover tends to sit in the low single digits because large plant and equipment bases are required. In contrast, software firms or digital platforms often enjoy double‑digit turnovers thanks to relatively light asset bases.
When evaluating a single company, watch for trends:
- If the ratio climbs year over year, the business is likely improving its asset utilization or generating more sales without proportionally increasing capital.
- A downward drift could signal over‑investment, under‑utilized capacity, or a shift toward lower‑margin products.
- Sudden spikes might be temporary—perhaps a large contract boosted sales—but they can also indicate that the capital base was temporarily low due to asset disposals.
Using the Metric in Decision‑Making
Invested capital turnover isn’t a standalone verdict; it works best alongside related ratios. Pair it with return on invested capital (ROIC) to see not just how much revenue each dollar generates, but how much profit it ultimately creates. A company with a high turnover but a low ROIC may be selling a lot but at thin margins.
Investors can also apply the metric when assessing mergers and acquisitions. If a target’s turnover is significantly higher than the acquirer’s, the deal might bring valuable efficiency gains—provided cultural and operational integration can be achieved.
From a managerial perspective, the ratio can guide budgeting. Suppose a division’s turnover lags the corporate average; leadership might prioritize process improvements, automation, or even divestiture if the assets cannot be better utilized.
Common Pitfalls to Avoid
Even a useful metric can mislead if you overlook its nuances. First, be wary of “window‑dressing”—companies sometimes reclassify expenses to shrink invested capital artificially, inflating turnover. Second, remember that the ratio ignores profitability; a firm could have a stellar turnover but be hemorrhaging cash due to high operating costs.
Finally, compare apples to apples. Adjust for accounting differences, especially when looking across borders where definitions of “invested capital” may vary.
Quick FAQ
Q: How does invested capital turnover differ from asset turnover?
A: Asset turnover uses total assets, which include non‑interest‑bearing items like cash reserves. Invested capital turnover focuses on the portion of assets financed by debt or equity, offering a clearer view of the capital actually deployed in the business.
Q: Can a low turnover ever be a good sign?
A: In capital‑intensive sectors, a modest turnover is normal. The key is whether it aligns with industry benchmarks and whether it’s improving relative to the company’s own history.
Q: Should I look at quarterly or annual turnover?
A: Annual figures smooth out seasonal fluctuations and are generally more reliable for trend analysis. Quarterly data can be useful for spotting short‑term shifts, but they should be interpreted with caution.
Q: Is invested capital turnover useful for startups?
A: Early‑stage firms often have volatile capital structures, making the ratio less stable. However, as a startup matures and its capital base stabilizes, the metric becomes a valuable gauge of scaling efficiency.