Why FDIC-Insured Savings Accounts Are Your Money’s Safe Haven
When you tuck cash into a savings account, you’re hoping the bank will keep it safe, pay a modest interest, and make it available when you need it. The FDIC (Federal Deposit Insurance Corporation) steps in as the backstop, guaranteeing deposits up to a statutory limit. That guarantee turns an ordinary savings vehicle into a genuine safe haven for most everyday savers.
What Makes an Account FDIC-Insured?
Not every financial product carries FDIC protection. The key criteria are simple:
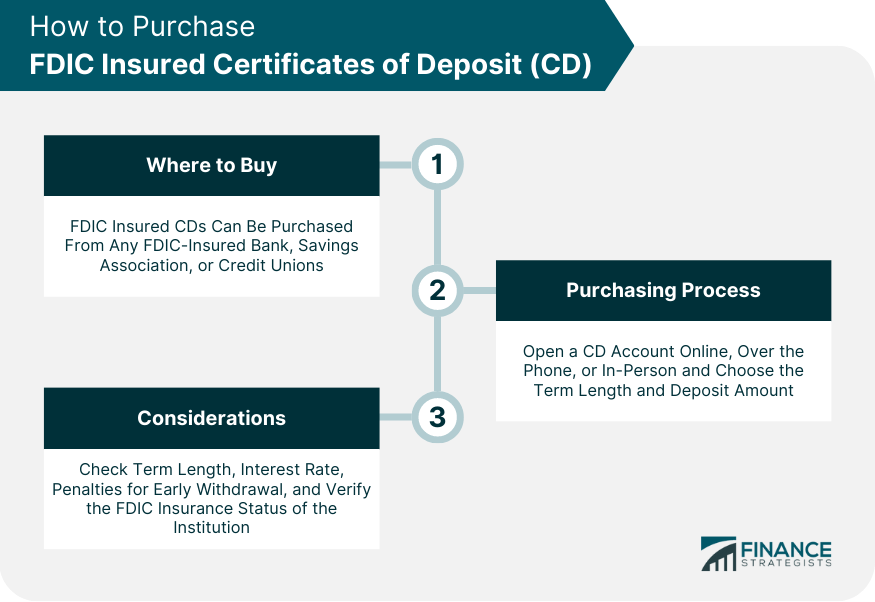
- The account must be a deposit product—savings, checking, money‑market, or certificates of deposit (CDs) offered by a member bank.
- The bank itself must be an FDIC member, which most U.S. depository institutions are.
- The depositor must be a natural person, partnership, corporation, or certain trusts; the insurance applies per owner, not per account.
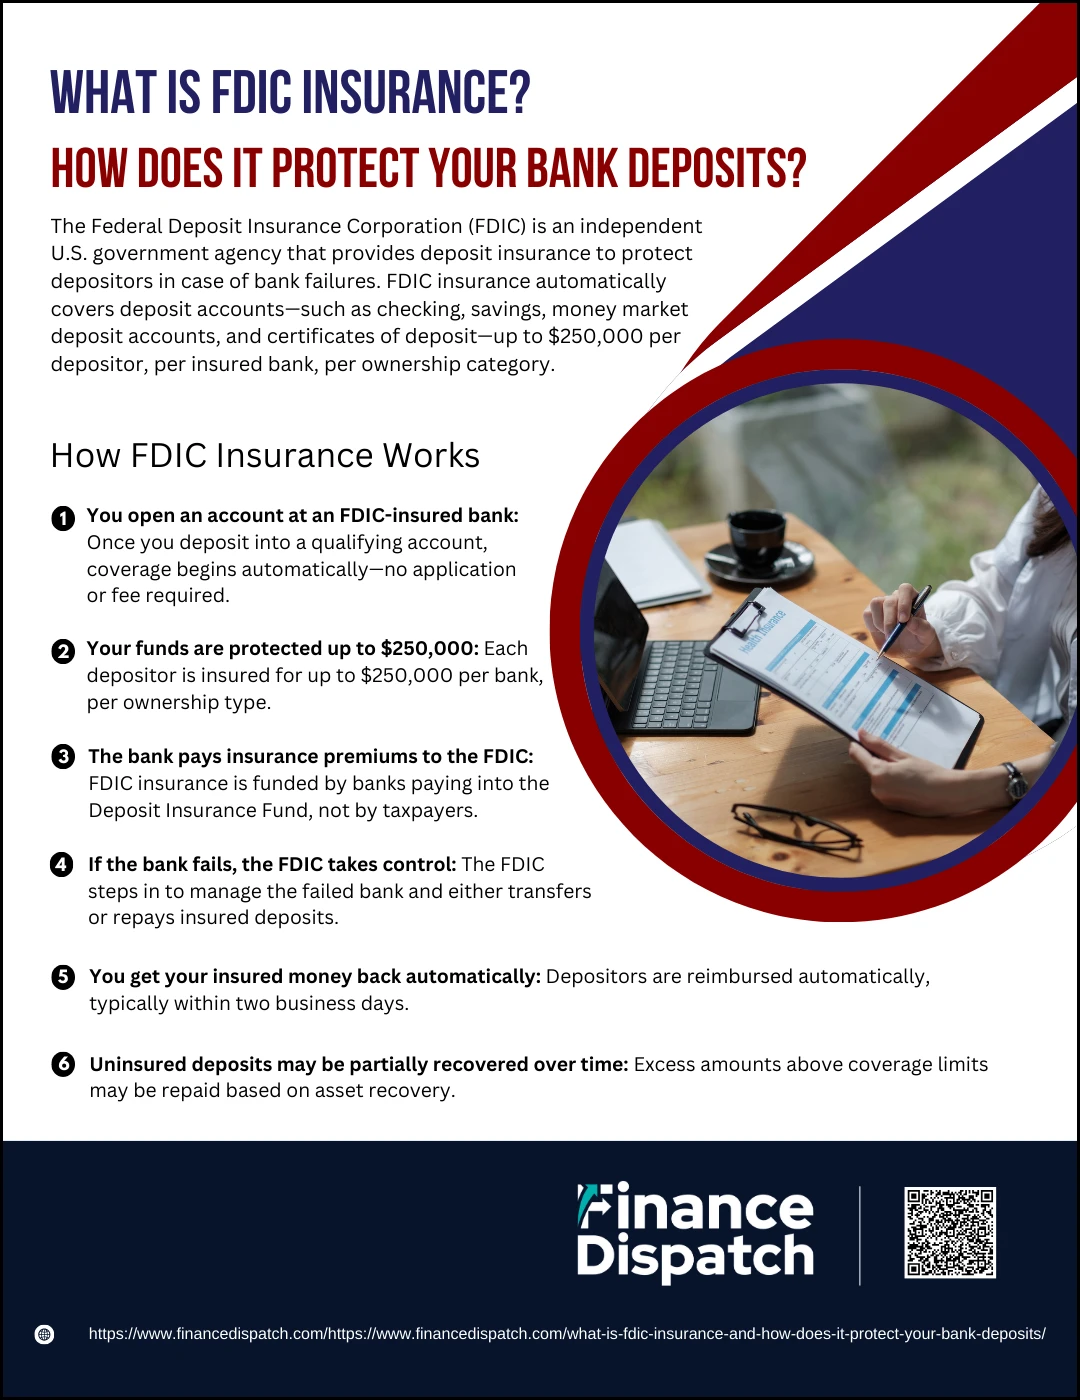
If those boxes are checked, the Federal Deposit Insurance Corporation automatically insures the balance up to $250,000 per depositor, per insured bank. The coverage is per “ownership category,” meaning you could have $250,000 in a single‑ownership savings account and another $250,000 in a joint account at the same bank, and both would be fully protected.
How FDIC Coverage Works in Practice
Imagine you have $180,000 sitting in a high‑yield savings account at a community bank. If that bank were to fail, the FDIC would step in, reimburse you for the full amount, and either transfer your deposits to another healthy institution or issue a check. The whole process typically finishes within a few days, and you keep earning interest on the new account.
Because the insurance limit is per depositor, you can diversify across multiple banks to expand coverage. For example, splitting $500,000 evenly among three different FDIC‑insured banks would keep each $166,667 under the $250,000 ceiling, effectively safeguarding the entire sum.
It’s also worth noting that the FDIC does not insure securities, mutual funds, or cryptocurrencies—even if they’re offered through a bank’s investment platform. Those assets sit outside the safety net and can lose value if the institution collapses.
Choosing the Right FDIC-Insured Savings Account
While the insurance itself is a non‑negotiable safety feature, the account’s terms still matter. Here are three factors to weigh before you click “Open Account.”
Interest Rate and Compounding Frequency
High‑yield online banks often post rates well above the national average, sometimes double the traditional brick‑and‑mortar offers. Pay attention to how often interest compounds—daily compounding can eke out a noticeable boost over monthly.
Fees and Minimum Balances
Many FDIC‑insured savings accounts are fee‑free, but a handful still charge monthly maintenance fees or require a minimum balance to avoid them. A $5 fee on a $1,000 balance erodes your earnings faster than a marginally lower interest rate would.
Accessibility and Transfer Options
Consider how quickly you can move money in and out. Some accounts limit withdrawals to six per month (a relic of Regulation D), while others offer unlimited transfers via linked checking accounts or external ACH.
Balancing these criteria against your personal savings goals—whether you’re building an emergency fund, stashing a down‑payment, or simply parking cash for short‑term needs—will help you select the safest, most rewarding account.
Common Misconceptions About FDIC Insurance
Even seasoned savers sometimes carry myths about the FDIC. Let’s debunk a few:
- “FDIC insurance is a government bailout.” In reality, the FDIC is funded by premiums paid by member banks, not by taxpayer dollars.
- “All bank products are insured.” Only deposit accounts qualify. Brokerage accounts, investment advisory services, and crypto wallets are excluded.
- “I’m safe as long as the bank is big.” Size offers no guarantee; any FDIC‑member bank, large or small, is covered up to the statutory limit.
Understanding these nuances prevents unnecessary panic and helps you make smarter allocation decisions.
Practical Steps to Maximize Your Protection
1. Verify Membership. Look for the FDIC logo on the bank’s website or use the FDIC’s “BankFind” tool to confirm coverage.
2. Calculate Your Ownership Categories. If you hold joint accounts, retirement accounts, and trust accounts, each category has its own $250,000 limit.
3. Spread Your Funds. Use multiple banks or credit unions to keep each institution’s balance under the limit.
4. Review Statements Regularly. A sudden change in account type or a merger can affect your insurance status.
5. Stay Informed. The FDIC updates its rules occasionally; a brief yearly check can keep you ahead of any changes.
FAQ
Is the $250,000 limit per person or per account?
The limit applies per depositor, per insured bank, per ownership category. So you could have $250,000 in a single‑ownership savings account and another $250,000 in a joint account at the same bank, both fully covered.
Do credit unions offer similar insurance?
Yes—credit unions are protected by the NCUA (National Credit Union Administration), which also insures deposits up to $250,000 per member.
Can I lose money on an FDIC‑insured account?
Only if the bank’s balance exceeds the insured limit. Within the $250,000 cap, you’re protected even if the bank fails. However, the account’s interest rate may be low, so inflation can erode purchasing power over time.
What happens if I have more than $250,000 in one account?
Amounts above the limit become uninsured. In a failure scenario, the FDIC would return the insured portion, and the excess could be lost or recovered through the bank’s liquidation process, which may take months or years.