Medicare Insurance Explained: What You Need to Know
When the calendar turns to age 65, many of us begin to hear the phrase “Medicare” more often than we’d like. It can feel like a jumble of letters and numbers, but at its core, Medicare is a federal health insurance program designed to protect seniors and certain younger people with disabilities. This article breaks down the basics of Medicare insurance, the different parts of the program, and practical tips for choosing the right coverage.
Medicare Insurance Explained: Key Facts
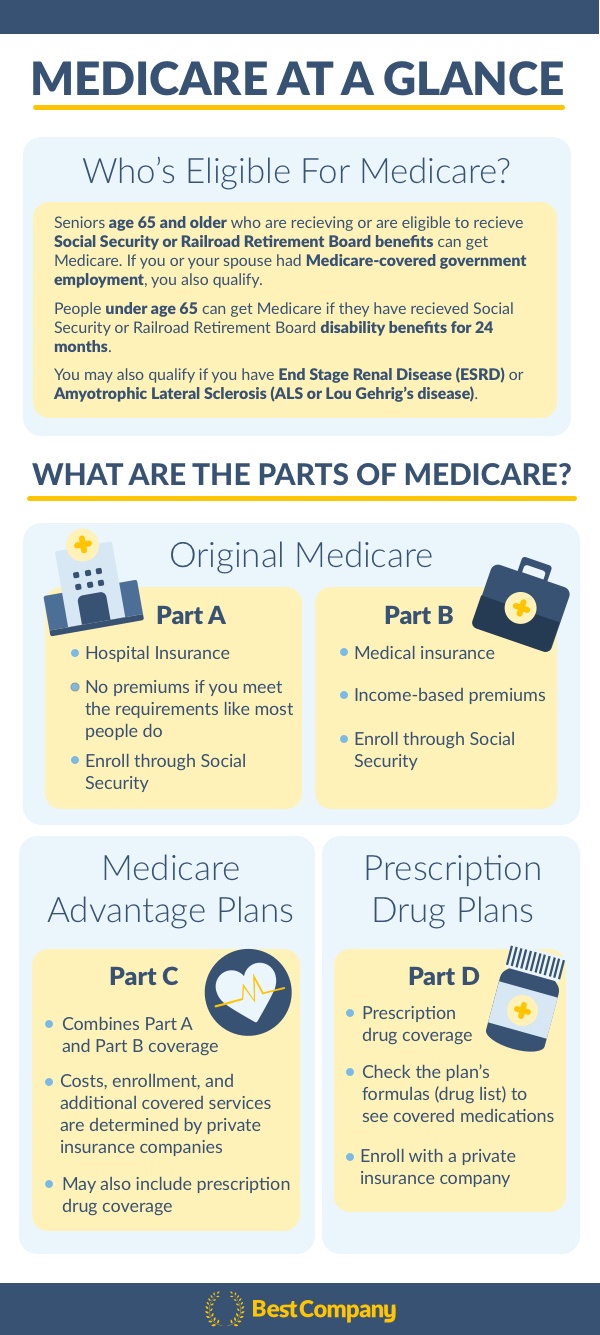
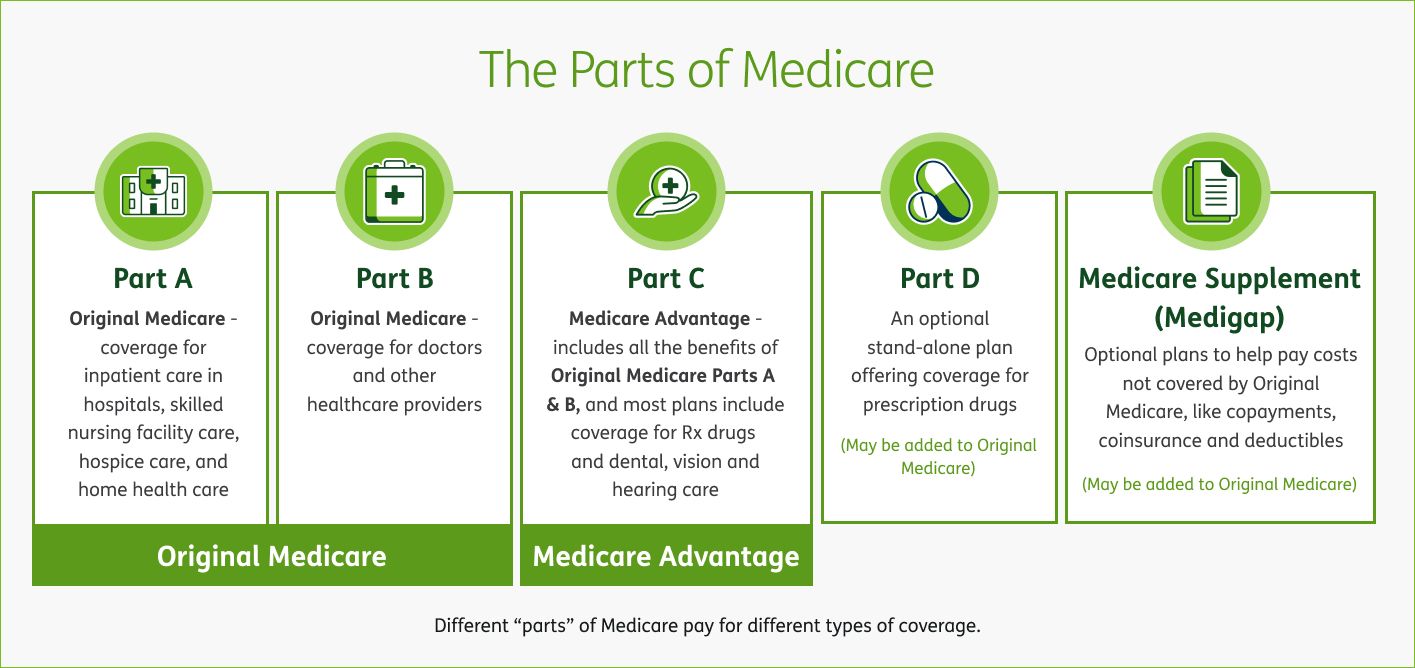
Medicare isn’t a single policy but a set of programs that cover different health needs. Understanding the four primary parts—A, B, C, and D—helps you decide which options fit your health profile and budget.
- Part A (Hospital Insurance): Covers inpatient hospital stays, skilled nursing facility care, hospice, and some home health services.
- Part B (Medical Insurance): Pays for doctor visits, outpatient care, preventive services, and medical supplies.
- Part C (Medicare Advantage Plans): Private‑sector plans that combine Parts A and B and often add Part D and extra benefits like vision or dental.
- Part D (Prescription Drug Coverage): Lowers the cost of prescription medications through a network of pharmacies and drug manufacturers.
Most people automatically enroll in Parts A and B when they turn 65, but the rest of the choices require active decision‑making.
How the Enrollment Process Works
Enrollment opens in three windows: the Initial Enrollment Period, the General Enrollment Period, and Special Enrollment Periods. The Initial Enrollment Period begins three months before the month you turn 65 and lasts for seven months. Missing this window can lead to higher premiums or gaps in coverage.
Special Enrollment Periods allow you to sign up for or change plans if you’re moving, losing other coverage, or experiencing significant life changes. Knowing which window you’re in can save you money and reduce paperwork.
Choosing Between Original Medicare and Medicare Advantage
Original Medicare (Parts A and B) offers flexibility: you can visit any provider that accepts Medicare. However, you’ll often pay coinsurance or deductibles out of pocket and need a separate prescription plan.
Medicare Advantage (Part C) bundles these services into a single plan, sometimes with extra perks such as free gym memberships or telehealth visits. Many plans also include prescription coverage, eliminating the need for a separate Part D plan.
When deciding, consider:
- Cost: Compare premiums, deductibles, and out‑of‑pocket limits.
- Provider network: Does the plan cover your preferred doctors and hospitals?
- Prescription needs: Does the plan’s drug formulary match your medication list?
- Additional benefits: Dental, vision, wellness programs, and travel insurance can tip the scale.
Understanding Your Prescription Drug Coverage
Prescription drug costs can be a major concern. Part D plans come in various formularies—lists of covered drugs—categorized into tiers. Tier 1 drugs are usually generic and have the lowest copay; tier 5 or specialty drugs can be expensive.
Some Medicare Advantage plans include Part D, while others offer a separate plan. Always review the formulary and consider whether your current medications fall within the tier structure before enrolling.
Managing Out‑of‑Pocket Expenses
Each year, Medicare sets a maximum out‑of‑pocket limit for Original Medicare beneficiaries. Once you reach this ceiling, Medicare pays 80% of covered services for the rest of the year. Medicare Advantage plans typically have a lifetime dollar‑limit on out‑of‑pocket spending.
Planning ahead can prevent surprises:
- Track your deductible status: Some plans allow you to monitor your progress online.
- Use preventive services: Most preventive visits are covered at no cost, keeping your health in check without extra expenses.
- Appeal denied claims: If a claim is rejected, you have a process for reviewing and appealing the decision.
Common Misconceptions About Medicare
Many people think Medicare is free. Part A is typically free if you or your spouse paid Medicare taxes while working for at least 10 years, but Part B carries a monthly premium that can vary by income. Likewise, prescription coverage is not automatic; you must enroll separately.
Another myth is that Medicare Advantage plans are always cheaper. While many are cost‑effective, they can restrict provider choice or require you to stay within a narrow network. Conversely, Original Medicare offers broader access at the cost of managing separate plans.
Frequently Asked Questions
1. Do I have to enroll in Part D if I already have a Medicare Advantage plan?
Not necessarily. If your Advantage plan includes prescription coverage, you can opt out of a separate Part D plan. Check the plan’s drug formulary to ensure it meets your needs.
2. What happens if I miss the Initial Enrollment Period?
You may still enroll during the General Enrollment Period (January 1–March 31) but will face a 2‑month late‑enrollment penalty that increases your Part B premium by 15% each year you were late.
3. Are preventive screenings covered at no cost?
Yes, most preventive services—such as mammograms, colonoscopies, and flu shots—are covered with no deductible or copay.
4. How do I decide between Original Medicare and Medicare Advantage?
Consider your healthcare habits, preferred doctors, medication list, and budget. If you value flexibility and have reliable doctors, Original Medicare plus a separate Part D plan may suit you. If you want bundled coverage and extra perks, a Medicare Advantage plan could be better.