Understanding Income Tax Expense: A Straight‑Forward Guide
When a business talks about income taxes expense, most people picture a bank account draining or a ledger line that seems to grow with every profit surge. In reality, income tax expense is a calculable figure that reflects the tax burden a company expects to pay on its taxable income for a given period. By unpacking its components—gross income, deductions, tax rates, and credits—business owners can forecast cash needs, plan capital investments, and avoid surprises when the tax bill arrives.
Income Tax Expense Explained
At its core, income tax expense is the amount a company records on its income statement to represent the taxes it will pay to the government in the current year. It is not the same as the actual cash paid; that cash outflow is often spread across multiple installments or even deferred into future periods.
How Companies Record It
- Tax Provision – A provisional estimate, updated as new information emerges.
- Deferred Tax Assets/LIabilities – Timing differences between book and tax rules that will affect future periods.
Key Drivers of the Expense
Several factors can push the number up or down. A robust revenue stream can increase the tax base, but so can strategic deductions. Tax credits can directly reduce the expense, sometimes turning a large tax bill into a credit that offsets other costs.
Calculating the Expense for Your Company
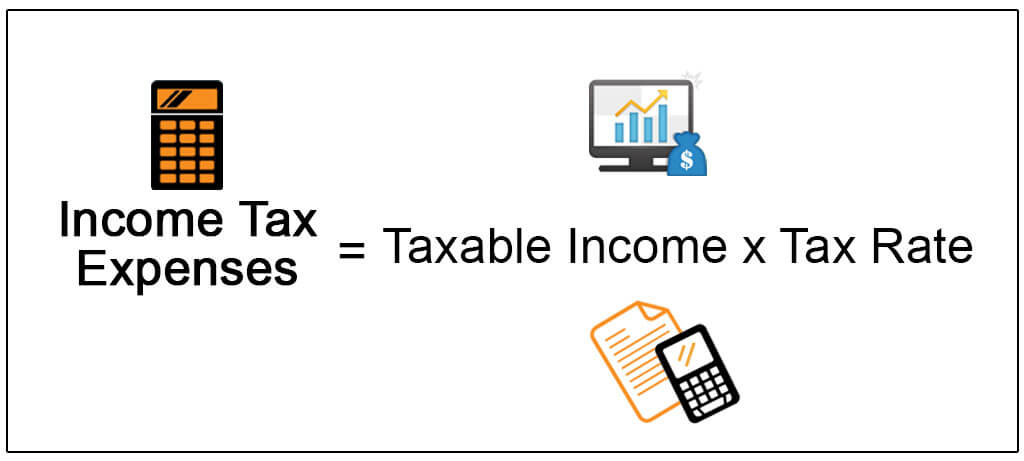
The calculation follows a logical path: start with gross income, subtract allowable deductions, apply the relevant tax rate, and then subtract any credits.
Step 1 – Determine Taxable Income
Take the company’s gross income and add back any non-deductible expenses (e.g., certain fines or entertainment expenses). Next, subtract business expenses that the tax code permits, such as salaries, rent, utilities, and depreciation.
Step 2 – Apply the Tax Rate
Federal, state, and local governments each impose their own rates. For a typical corporation, the federal corporate tax rate might be 21%, but combined with state taxes the effective rate can hover around 30% in many jurisdictions.
Step 3 – Factor in Credits
Tax credits are direct reductions in tax expense. Common credits include research and development, low-income housing, and investment in renewable energy. Credits can sometimes exceed the tax liability, creating a net credit that flows into the next period.
Step 4 – Adjust for Timing Differences
Because books and tax rules often treat certain expenses differently, deferred tax assets and liabilities arise. For example, depreciation methods may differ, creating a future tax advantage or disadvantage.
Common Deductions That Reduce the Expense
Understanding which costs actually lower your tax expense is essential. Some of the most significant deductions include:
- Employee compensation and benefits
- Business travel and meals (subject to limits)
- Interest paid on business loans
- Amortization of intangible assets
- Charitable contributions (within statutory limits)
The Role of Tax Credits
Credits are often the most powerful tool for lowering tax expense because they reduce the tax owed dollar‑for‑dollar. The R&D credit, for example, can offset a large portion of a company’s tax burden. Always keep an eye on the evolving credit landscape; new incentives appear with each tax reform cycle.
Managing the Expense Over Time
Income tax expense isn’t a static number. Companies must adjust their projections each quarter, especially as income swings or new deductions become available.
Quarterly Estimates
Many jurisdictions require quarterly prepayments based on estimated tax liability. A miscalculated estimate can trigger penalties, so accurate forecasting is non‑negotiable.
Year‑End Adjustments
At the close of the fiscal year, actual numbers replace estimates. The difference between the estimated and actual tax expense is recorded as an adjustment entry, which can influence cash flow forecasts for the next year.
Cash Flow Implications
Because tax payments can be substantial, aligning them with cash inflows is crucial. Companies often use escrow accounts or tax‑specific lines of credit to smooth the impact on day‑to‑day operations.
Reporting on the Financial Statements
Income tax expense appears on the income statement as a line item beneath operating income. It also influences the balance sheet through deferred tax assets or liabilities.
- Income Statement – Shows the total tax expense for the period.
- Balance Sheet – Lists deferred tax balances that will affect future statements.
Common Pitfalls to Avoid
Even seasoned accountants can slip. These errors can inflate or deflate the tax expense, leading to mis‑budgeting.
- Underestimating Deductions – Failing to capture all eligible expenses.
- Misclassifying Income – Treating passive income as active business income can raise the tax base.
- Ignoring Credits – Overlooking available credits can cost a company valuable savings.
- Late Payments – Penalties can quickly erode the tax benefit.
Frequently Asked Questions
What’s the difference between tax expense and tax liability?
Tax expense is the amount recorded on the income statement; tax liability is the actual amount owed to tax authorities.
Can a company defer its income tax expense?
Yes, through mechanisms like installment payments or deferring certain deductions that create future tax advantages.
How do state taxes factor into income tax expense?
State taxes are added to the federal tax base and applied at the state's statutory rate, creating a combined effective rate.
Are there penalties for overestimating tax expense?
No, but overpayment can tie up cash unnecessarily. Underpayment can trigger penalties and interest.