Understanding ASB Home Loan Rates: What You Need to Know
When you start looking at property financing, the first number that catches your eye is often the ASB home loan rates. Those rates determine how much you’ll actually pay over the life of the loan, and they can shift depending on a handful of moving parts. Below we break down the mechanics, the choices, and the little tricks that can help you lock in a more favourable deal.
How ASB Sets Its Home Loan Rates
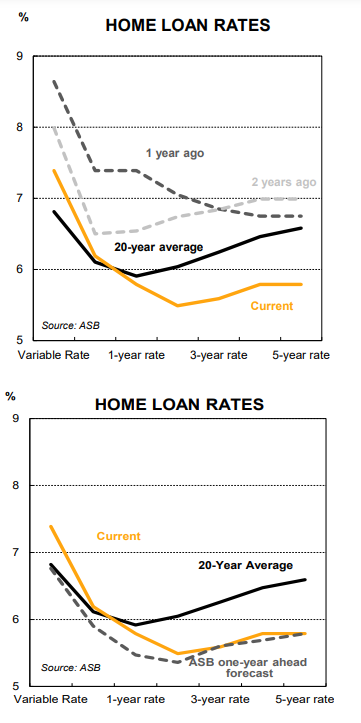
ASB, like most banks, bases its mortgage pricing on the official cash rate set by the Reserve Bank of New Zealand, plus a margin that reflects its own funding costs and risk appetite. When the central bank nudges the cash rate up or down, you’ll usually see a corresponding change in the advertised variable rates within a month or two.
Beyond that baseline, ASB layers in adjustments for loan‑to‑value (LTV) ratios, credit history, and the type of property you’re buying. A borrower with a low LTV—say, 70 % or less—might enjoy a discount of a few tenths of a percent, while a higher‑risk profile could add a premium.
Fixed vs Variable Options
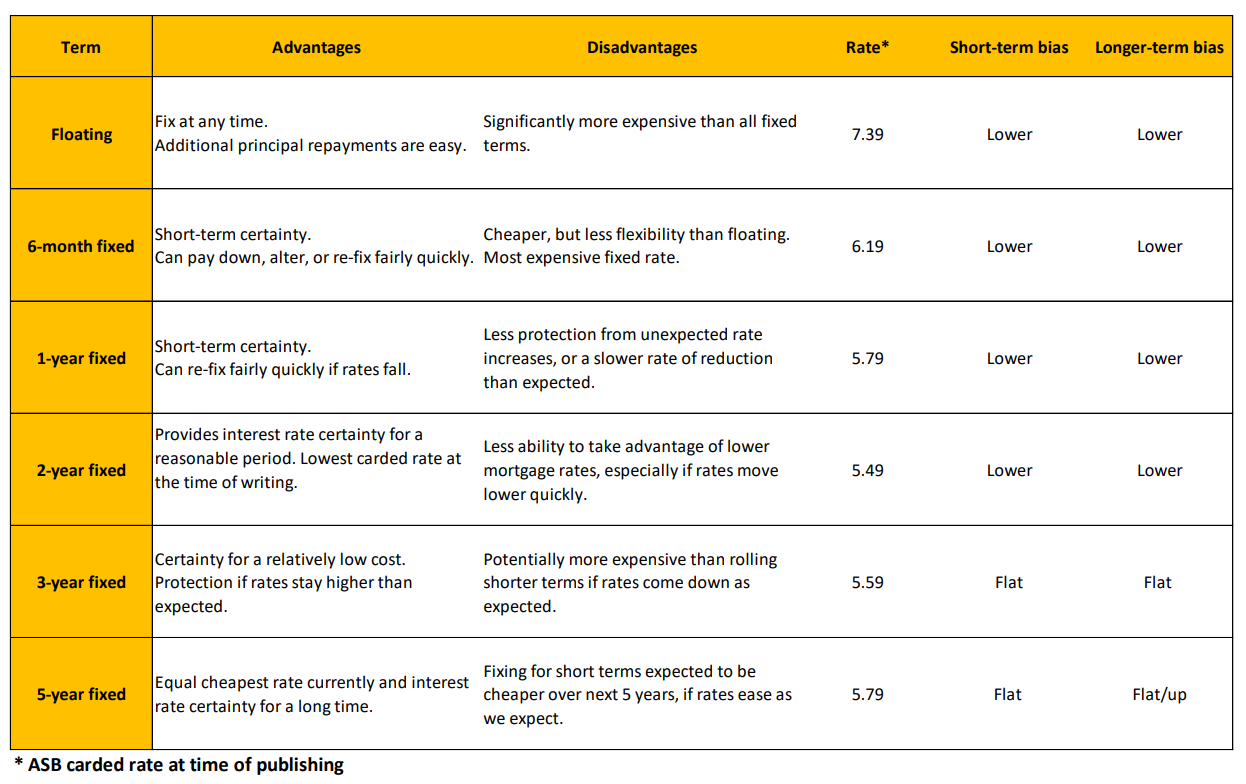
ASB offers both fixed‑term and variable‑rate home loans. A fixed rate locks your interest for a set period—commonly two, three, or five years—so you know exactly what the repayments will be, regardless of market swings. The trade‑off is usually a slightly higher rate than the variable baseline and a potential exit fee if you want to refinance early.
Variable loans, on the other hand, track the bank’s current pricing. If the cash rate drops, your repayments could fall; if it rises, you’ll feel the pinch. Many borrowers appreciate the flexibility to make extra repayments without penalty, which can shave years off the loan term.
Factors That Influence Your Rate
- LTV ratio: The lower the loan amount relative to the property value, the less risk for the bank, often translating into a lower rate.
- Credit score: A clean credit file signals reliability, earning you a discount on the base rate.
- Loan purpose: Owner‑occupied homes typically attract better rates than investment properties.
- Deposit size: Larger deposits can unlock promotional rate offers or reduced margins.
- Loan term: Shorter terms (e.g., 20 years) may be priced lower than longer 30‑year terms because the bank’s exposure is reduced.
Tips for Getting a Better Deal
Even if you’re not a mortgage guru, a few simple steps can shave a noticeable amount off your interest cost.
- Shop around before committing. Use ASB’s online rate calculator to get a baseline, then compare with other major lenders.
- Boost your deposit. Moving from an 80 % to a 70 % LTV can net you a discount of 0.2–0.3 percentage points.
- Check your credit report. Correct any errors, and consider paying down existing debts to improve your score.
- Ask about discounts for existing customers or for bundling products like a transaction account.
- Consider a split loan—part fixed, part variable—to balance certainty with flexibility.
Common Misconceptions About Mortgage Rates
Many first‑time buyers assume the advertised rate is the whole story, but that’s rarely the case. The “interest rate” you see doesn’t include fees such as loan establishment, valuation, or legal costs, which can add several thousand dollars to the overall expense. Likewise, a low variable rate doesn’t automatically mean cheaper repayments if you have a high LTV and a modest credit score.
Another frequent myth is that refinancing only makes sense when rates drop dramatically. In reality, even a modest reduction—say, 0.25 percentage points—can be worthwhile if you’re able to avoid early‑exit fees and you plan to stay in the property for a few more years.
When to Lock in a Fixed Rate
If you prefer budgeting certainty, a fixed rate can be a smart move, especially when the market signals an upcoming rise in the cash rate. ASB typically releases its fixed‑rate offerings ahead of the official rate changes, giving borrowers a window to lock in lower pricing.
However, if you anticipate a rate cut or you’re comfortable with fluctuating payments, staying on a variable loan may let you benefit from any downward movement. Keep an eye on the Reserve Bank’s monetary policy statements—they often give clues about the direction of interest rates.
How to Monitor Your Mortgage Over Time
Signing a mortgage isn’t the end of the story. ASB provides an online dashboard where you can track your balance, view interest calculations, and even run “what‑if” scenarios to see how extra repayments would affect the term.
Set a reminder to review your loan every 12 months. Market conditions change, and a better rate may be available without the need for a full‑blown refinance. A quick call to your loan officer can sometimes unlock a temporary discount or a promotional rate that isn’t publicly advertised.
FAQ
What is the typical range for ASB’s variable home loan rates in 2024?
Generally, they sit between 5 % and 6 % per annum for standard borrowers, but exact pricing depends on LTV, credit history, and loan purpose.
Can I switch from a variable to a fixed rate without penalties?
ASB allows rate switches, but there may be an administrative fee and, for fixed‑term contracts, an early‑exit charge. It’s worth asking for a fee waiver if you’re moving to a comparable product.
Do I need a mortgage broker to get the best ASB rate?
Not necessarily. Direct applications through ASB’s website are straightforward, but a broker can sometimes negotiate a marginally better margin, especially if you have a complex financial situation.
How often does ASB update its home loan rates?
Rate adjustments typically follow the Reserve Bank’s cash‑rate announcements, which occur about once a month, though ASB may fine‑tune its margins more frequently based on market conditions.