Key Takeaways from the 2015 Franchise Prospect Survey
The 2015 Franchise Prospect Survey newsletter compiled responses from more than a thousand aspiring franchisees, offering a rare snapshot of who was looking to buy, why, and what obstacles they faced. Readers of the newsletter expected practical guidance, so the analysis focuses on the most actionable trends rather than a laundry‑list of statistics. Below, we break down the insights that still matter to franchisors and investors alike.
Insights from the 2015 Franchise Prospect Survey Newsletter
Overall, the 2015 survey revealed a shifting mindset among prospects. While the desire for entrepreneurship remained strong, confidence in the franchise model itself showed subtle cracks, especially in regions hit hard by the lingering recession. Understanding these nuances helps franchisors tailor their outreach and support structures.
Who Was Surveyed?
Respondents ranged from recent college graduates to seasoned small‑business owners. Roughly 42 % were under 35, suggesting a younger wave eager to avoid the pitfalls of starting a brand from scratch. About 28 % reported prior experience managing a restaurant or retail outlet, indicating that operational know‑how still matters when evaluating franchise opportunities.
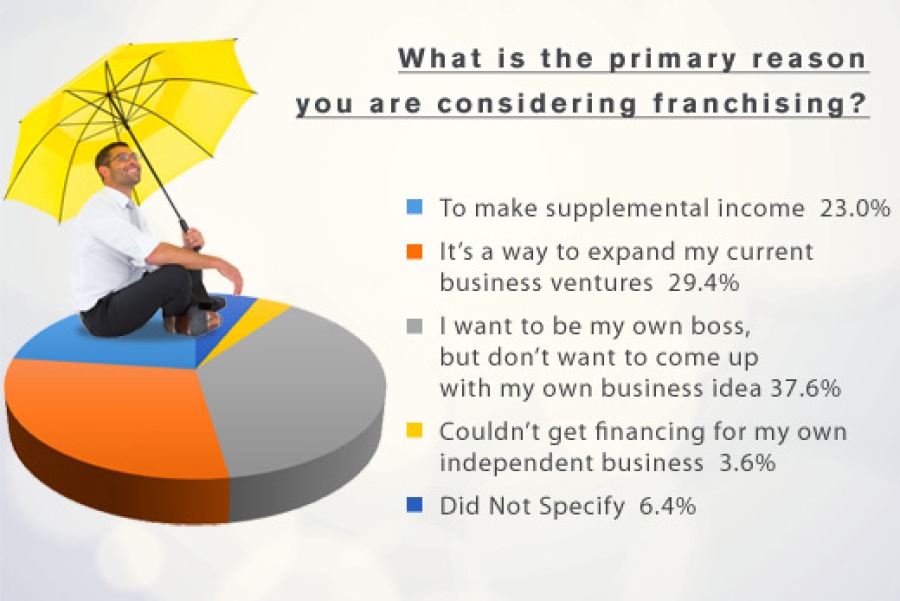
Primary Motivations for Pursuing a Franchise
- Brand Recognition: More than half of the participants cited an established name as the main draw, hoping it would shorten the learning curve.
- Support Systems: Training programs and ongoing assistance ranked just behind brand power, especially for those with no previous business ownership.
- Financial Predictability: Prospects appreciated the ability to benchmark earnings against disclosed unit economics, a luxury rarely afforded by independent startups.
Financing Hurdles That Still Stood Out
Even with strong interest, securing capital proved to be the single biggest barrier. Approximately 37 % of respondents said they were “still searching” for financing, while 22 % relied on personal savings and family contributions. The survey highlighted three recurring challenges:
- Limited access to SBA loans in certain states, where local banks were hesitant to back franchise concepts.
- Higher-than‑expected down‑payment requirements, often exceeding 30 % of total investment.
- Uncertainty about franchise‑specific financing options, leading many prospects to delay their decisions.
Industry Preferences Among 2015 Prospects
When asked which sectors they favored, respondents gravitated toward three categories:
- Quick‑service food and beverage – Still the dominant choice, driven by perceived low startup costs and high foot traffic.
- Health‑and‑wellness – A growing segment, especially among younger prospects interested in boutique fitness and nutrition.
- Home‑service franchises – Including cleaning, landscaping, and senior care, reflecting an aging population and increasing demand for convenience.
Regional Variations Worth Noting
Geography mattered more than many franchisors assumed. The Southeast showed a pronounced appetite for food‑service concepts, while the Pacific Northwest leaned heavily toward eco‑friendly and health‑focused brands. Meanwhile, the Midwest displayed a balanced mix, with a notable tilt toward home‑service franchises that catered to both urban and rural markets.
Implications for Franchisors
These findings suggest a two‑pronged approach for franchisors looking to attract qualified prospects:
- Tailor Messaging: Emphasize brand support and training in regions where experience levels are low, and highlight proven financial models where capital is scarce.
- Expand Financing Partnerships: Collaborate with lenders familiar with franchise structures to ease down‑payment burdens and streamline loan approvals.
Franchisors that adapt their recruitment strategies to these nuanced preferences are more likely to convert leads into successful franchisees.
How to Use These Insights in Your Own Franchise Strategy
First, audit your current prospect pipeline. Are you attracting the right demographic mix, or does your marketing skew older than the 42 % under‑35 segment identified in the survey? Next, evaluate your financing toolkit. If your down‑payment threshold exceeds industry norms, consider offering phased payment plans or partnering with financing firms that specialize in franchise deals.
Finally, align your industry focus with emerging consumer trends. While quick‑service remains a safe bet, integrating health‑oriented options or home‑service add‑ons can differentiate your brand and appeal to the growing segments highlighted in the 2015 data.
Frequently Asked Questions
What was the biggest obstacle for prospects in 2015?
Access to financing topped the list, with many respondents citing difficulty securing loans or meeting high down‑payment demands.
Did the survey show a preference for any particular franchise model?
Yes. The data pointed to a clear preference for turnkey, low‑maintenance models—especially in quick‑service food, health‑and‑wellness, and home‑service sectors.
How can franchisors improve prospect conversion rates?
By refining their messaging to address the specific motivations and concerns uncovered in the survey, and by easing financing hurdles through strategic lender partnerships.
Are the 2015 trends still relevant today?
While market conditions have evolved, the core drivers—brand recognition, support systems, and financing accessibility—remain central to prospect decision‑making.