IIAMANAH: Your Complete Guide to Islamic Finance in Australia
Islamic finance is no longer a niche confined to the Middle East; it has steadily found its footing in Australia’s multicultural economy. Whether you’re a devout Muslim looking for Sharia‑compliant banking or an investor curious about ethical alternatives, the landscape can feel a bit bewildering at first. This guide breaks down the essentials, highlights the pivotal role of the IIAMANAH initiative, and shows you how to navigate the sector with confidence.
What Is Islamic Finance in Australia?
At its core, Islamic finance adheres to principles derived from Islamic law, or Sharia. The most recognizable rule is the prohibition of riba—interest—meaning that profit must arise from genuine economic activity rather than a fixed return on a loan. In practice, Australian providers use structures such as murabaha (cost‑plus financing), ijara (leasing), and mudarabah (profit‑sharing) to meet these requirements.
The Australian market has grown steadily over the past decade. Major banks, including HSBC and ANZ, now offer Islamic windows, while a handful of boutique firms specialize exclusively in Sharia‑compliant products. Regulatory oversight comes from the Australian Securities and Investments Commission (ASIC) and the Australian Prudential Regulation Authority (APRA), which treat Islamic finance entities much like their conventional counterparts, with added scrutiny on compliance with Sharia guidelines.
The Role of IIAMANAH
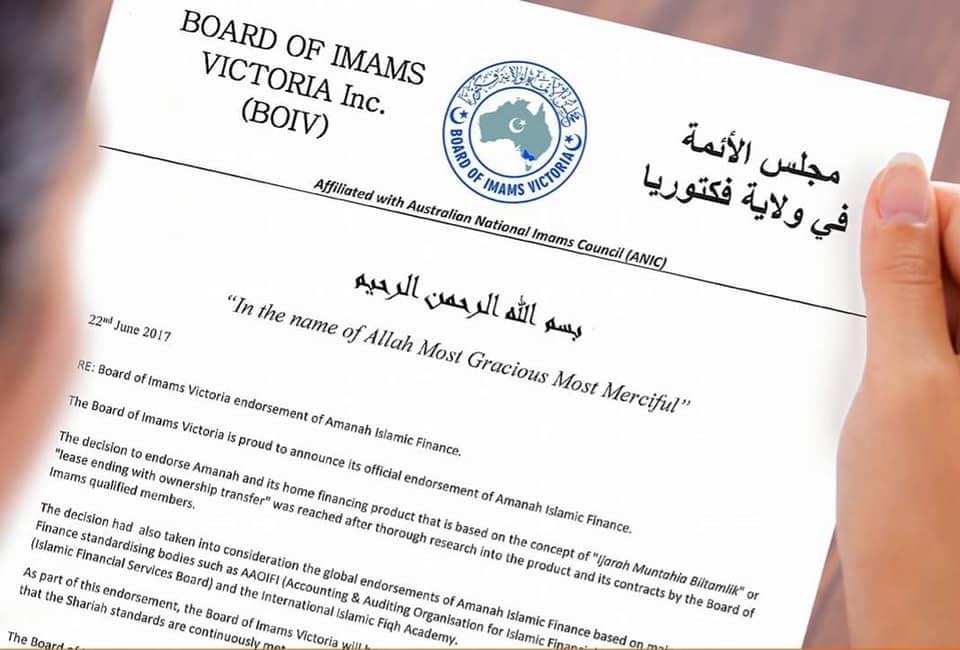
IIAMANAH—short for “Islamic Investment and Asset Management Authority”—acts as a bridge between scholars, regulators, and financial institutions. Established in 2019, its primary mission is to promote transparency and trust within the sector.
- Standard‑setting: IIAMANAH collaborates with recognised Sharia boards to develop consistent product criteria, reducing the risk of “green‑washing” where a product claims compliance without rigorous verification.
- Education: The organization runs webinars, publishes research briefs, and partners with universities to build a pipeline of professionals fluent in both finance and Islamic jurisprudence.
- Consumer advocacy: Through its “Ask‑A‑Scholar” portal, individuals can raise concerns about a product’s compliance and receive timely, scholarly feedback.
Because IIAMANAH is not a regulator, its authority stems from the credibility it has earned among scholars and market participants. When a bank proudly displays the IIAMANAH seal, consumers can feel a little more secure that the offering has undergone independent review.
Key Principles Guiding Islamic Finance
Understanding the philosophical backbone helps you evaluate any product more critically.
- Prohibition of Riba (interest): Earnings must stem from trade, investment, or service provision, not from charging interest on a loan.
- Risk‑sharing: Both the provider and the client share the upside and downside of an investment, aligning incentives.
- Asset‑backed transactions: Every financing arrangement must be tied to a tangible asset or service, preventing speculative excess.
- Ethical use of funds: Investments in industries deemed harmful—such as gambling, alcohol, or pork—are off‑limits.
These tenets are not abstract; they shape the contracts you’ll sign, the fees you’ll pay, and the disclosures you’ll receive.
How to Access Sharia‑Compliant Services
Finding a product that truly aligns with Islamic principles can feel like searching for a needle in a haystack, but a systematic approach makes it manageable.
- Identify accredited providers. Look for the IIAMANAH seal or references to a recognised Sharia board in the product documentation.
- Clarify the contract structure. Ask whether the financing uses murabaha, ijara, or another permissible model, and request a plain‑language summary.
- Check the asset link. Ensure the transaction is tied to a real asset—be it a house, vehicle, or equipment—rather than a cash loan.
- Review the fee schedule. While interest is prohibited, administrative fees are allowed if they reflect actual service costs.
- Seek scholarly confirmation. Use IIAMANAH’s “Ask‑A‑Scholar” service or consult a local mufti if you have lingering doubts.
Most banks now provide an online portal where you can compare conventional and Islamic product features side by side. If you’re a small business, consider partnering with a boutique firm that offers tailored mudarabah arrangements—these can be especially appealing for startups seeking profit‑sharing capital.
Common Misconceptions
Even seasoned investors sometimes stumble over myths that cloud judgment.
- “Islamic finance is more expensive.” While some products carry higher administrative fees due to added compliance steps, many studies show cost parity with conventional alternatives when you factor in the risk‑sharing benefits.
- “It’s only for Muslims.” The ethical framework appeals to a broader audience interested in socially responsible investing; non‑Muslims often choose Sharia‑compliant funds for their emphasis on real‑asset backing and avoidance of speculative sectors.
- “All Islamic banks are the same.” In Australia, the degree of compliance can vary. Some institutions simply avoid interest, while others embed comprehensive profit‑and‑loss sharing mechanisms. Scrutinising the underlying contract is essential.
Future Outlook for Islamic Finance in Australia
Industry analysts project modest but steady growth over the next five years. Demographic shifts, coupled with a global surge in ethical investing, suggest that demand for Sharia‑aligned products will continue to rise. The Australian government has taken tentative steps toward integrating Islamic finance into its broader financial strategy, including discussions on a dedicated regulatory sandbox that could accelerate product innovation.
Meanwhile, technology is playing a disruptive role. Fintech platforms are launching blockchain‑based sukuk (Islamic bonds) that promise greater transparency and faster settlement. For consumers, this means more choices and potentially lower barriers to entry.
Frequently Asked Questions
Is it possible to open a fully Sharia‑compliant bank account in Australia?
Yes. Several major banks operate Islamic windows that allow you to maintain a savings or transaction account without earning interest. Look for accounts that offer profit‑sharing returns instead of conventional interest.
Can I invest in Australian property through an Islamic finance structure?
Absolutely. Murabaha and ijara contracts are commonly used for residential and commercial real estate, enabling you to purchase property while adhering to Sharia principles.
What happens if a bank’s product is later deemed non‑compliant?
If a reputable Sharia board—such as the one affiliated with IIAMANAH—issues a non‑compliance ruling, the bank is typically required to amend the product or offer a corrective settlement to affected customers.
Do I need a religious scholar’s approval to use Islamic finance products?
While not mandatory, many individuals consult a trusted scholar or use IIAMANAH’s advisory services to ensure personal confidence in the product’s compliance.