How to Use ARR in Capital Budgeting: Research‑Backed Insights Made Easy
When you hear “ARR in capital budgeting,” you’re hearing a shortcut to gauge a project’s profitability without drowning in complex mathematics. Accounting Rate of Return (ARR) translates future cash flows into a single percentage, letting decision‑makers compare projects side‑by‑side. This guide walks through the fundamentals, highlights recent research on its reliability, and shows you how to apply ARR confidently in real‑world budgeting.
What Is ARR and Why It Still Matters
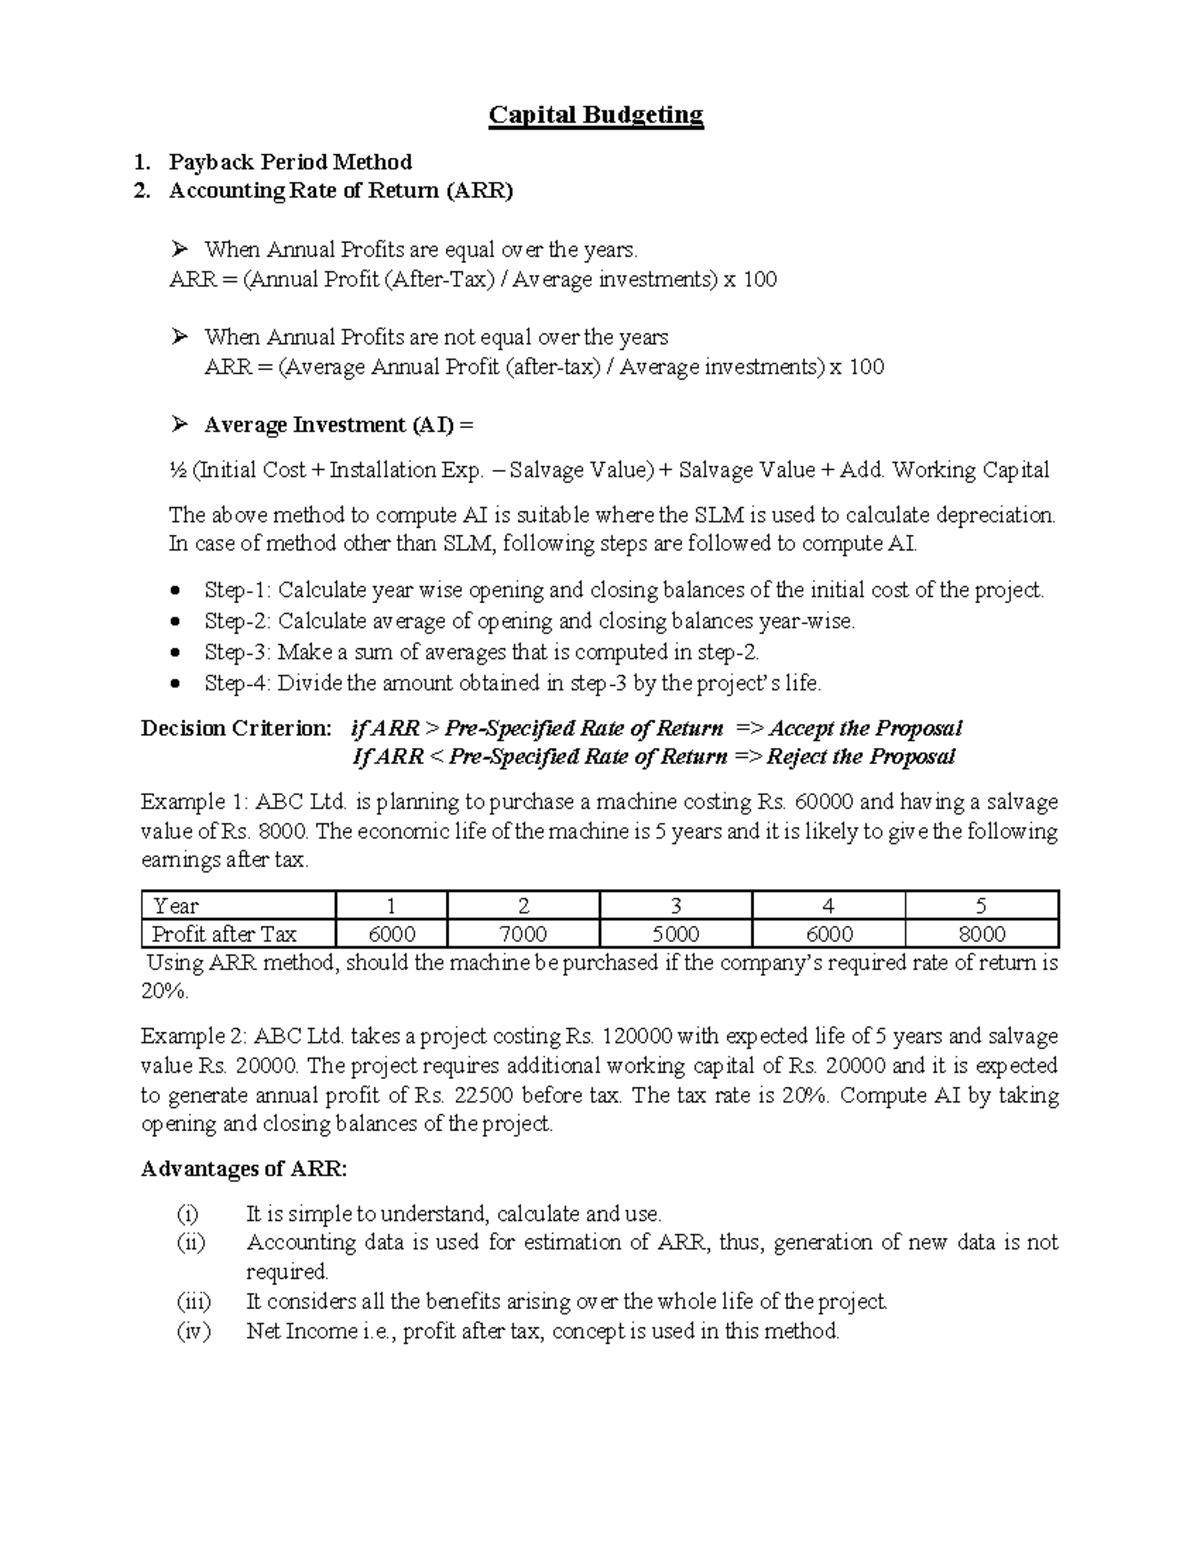
ARR is essentially the average accounting profit a project generates, expressed as a proportion of the initial investment. Unlike discounted‑cash‑flow methods, ARR leans on accounting earnings rather than cash flows, making it easier for finance teams that work primarily with income‑statement data. Though some critics argue it oversimplifies risk, many firms still rely on ARR for its clarity and speed, especially in early‑stage screening.
How to Calculate ARR: A Step‑by‑Step Walkthrough
Getting the number right is straightforward if you follow these steps:
- Estimate the project’s annual accounting profit (net income after depreciation).
- Calculate the average investment: (Initial cost + Expected salvage value) ÷ 2.
- Divide the average annual profit by the average investment, then multiply by 100 to get a percentage.
For example, a $500,000 project that yields $80,000 of accounting profit each year and has a salvage value of $50,000 would have an average investment of ($500,000 + $50,000) ÷ 2 = $275,000. ARR = ($80,000 ÷ $275,000) × 100 ≈ 29%.
What Recent Research Says About ARR’s Effectiveness
Academic and practitioner studies from the past decade reveal a nuanced picture. A 2022 survey of Fortune 500 CFOs found that 42% still use ARR as an initial filter before running more detailed net‑present‑value (NPV) analyses. Researchers at the University of Michigan noted that ARR’s simplicity can reduce “analysis paralysis,” helping firms move faster on low‑risk projects.
Conversely, a 2023 Journal of Corporate Finance article warned that ARR may overstate profitability for capital‑intensive ventures because it ignores the time value of money. The authors recommend pairing ARR with a quick payback test to catch projects that appear attractive on paper but cash‑flow poorly in the early years.
Advantages and Limitations: A Balanced View
Advantages
- Easy to compute using standard accounting data.
- Provides a quick, comparable metric across diverse projects.
- Helps non‑financial stakeholders understand profitability in familiar percentage terms.
Limitations
- Ignores cash‑flow timing, potentially misrepresenting long‑term value.
- Relies on accounting profit, which can be influenced by depreciation policies.
- Doesn’t explicitly factor in risk or cost of capital.
Because of these trade‑offs, most experts treat ARR as a screening tool rather than a final decision metric.
Practical Tips for Applying ARR in Your Capital‑Budgeting Process
Integrate ARR smoothly by following a few best practices:
- Set a clear benchmark.* Establish a minimum ARR threshold—say 15%—that aligns with your company’s required rate of return.
- Use consistent accounting policies.* Ensure depreciation methods and expense recognition are uniform across projects to avoid skewed comparisons.
- Combine with complementary analyses.* Pair ARR with payback period or a brief NPV check to capture time‑value considerations.
- Document assumptions.* Record the projected profit figures, salvage values, and any tax effects that feed into the calculation.
- Review annually.* As actual results materialize, compare them to the projected ARR and adjust future forecasts accordingly.
When to Favor ARR Over More Complex Metrics
ARR shines in situations where speed and simplicity outweigh precision. Typical scenarios include:
- Initial screening of dozens of minor upgrades or pilot projects.
- Budget discussions with senior leadership that prefer high‑level percentages.
- Industries with stable accounting margins, such as utilities or regulated services, where cash‑flow timing is less volatile.
If a project involves significant upfront outlays, long‑term cash‑flow uncertainty, or strategic importance, you’ll likely want to follow up with discounted‑cash‑flow methods.
Key Takeaways
ARR offers a quick snapshot of a project’s profitability, making it a valuable first‑look tool in capital budgeting. Recent research underscores its relevance for fast decision‑making while cautioning against overreliance. By setting clear benchmarks, maintaining consistent accounting practices, and pairing ARR with other simple metrics, you can harness its strengths without falling prey to its blind spots.
Frequently Asked Questions
How does ARR differ from IRR?
ARR measures average accounting profit relative to investment, whereas Internal Rate of Return (IRR) finds the discount rate that makes NPV zero, focusing on cash flows and time value.
Can I use ARR for projects with irregular cash flows?
It’s possible, but the metric may mask timing issues. Pairing ARR with a payback period or a brief NPV calculation helps reveal hidden risks.
What ARR threshold is considered “good”?
Thresholds vary by industry and cost of capital. Many firms aim for ARR above their weighted average cost of capital (often 10‑15%).
Is depreciation a major factor in ARR calculations?
Yes. Since ARR uses accounting profit, depreciation methods directly affect the numerator. Consistency across projects is essential for fair comparison.