How to Decode IPSE and Embedded SE Finance: Real-World Examples
When you first hear the terms IPSE and Embedded SE, the jargon can feel like a maze of acronyms. Decoding IPSE/EmbeddedSE finance examples isn’t just an academic exercise; it’s a practical skill that can unlock new revenue streams for fintech startups, SaaS platforms, and even traditional banks. In this guide we’ll peel back the layers, compare the two models, and walk through real‑world scenarios that show exactly how they operate. By the end, you should feel confident enough to spot opportunities and start mapping them onto your own product roadmap.
Understanding IPSE and Embedded SE Finance
IPSE stands for Integrated Payment Service Environment. Think of it as a white‑label payment stack that a non‑bank can embed directly into its user experience. The provider handles compliance, settlement, and risk, while the host brand retains the customer relationship. Embedded SE (Embedded Service Economics) is a broader concept that goes beyond payments— it includes credit, insurance, or investment products woven seamlessly into a primary service.
The key overlap is the “embedded” nature: the financial service feels native, not an afterthought. The difference lies in scope— IPSE is usually payment‑centric, whereas Embedded SE can cover any financial product that adds value to the core offering.
Key Differences in How They Work
- Regulatory footprint: IPSE providers often hold a banking or e‑money license, shielding the host from direct regulator scrutiny. Embedded SE may involve multiple licences, especially when credit or insurance is part of the mix.
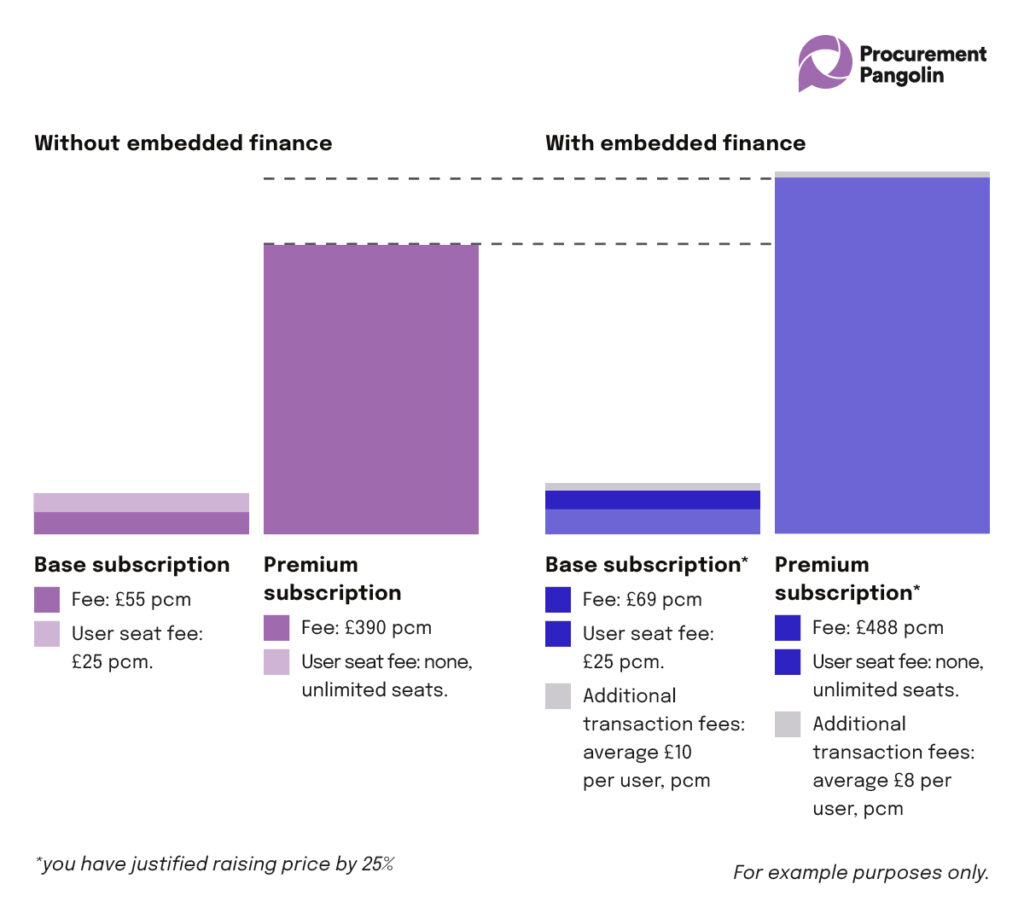
- Revenue model: IPSE typically charges per transaction or a flat monthly fee. Embedded SE can blend transaction fees with profit‑sharing on loan interest or insurance premiums.
- Customer data flow: With IPSE, the host usually sees only transaction status. Embedded SE platforms may exchange richer data—credit scores, usage patterns—to tailor offers.
- Implementation depth: IPSE often drops in as an API layer. Embedded SE might require UI redesign, underwriting workflows, and ongoing compliance monitoring.
Real-World Examples to Illustrate the Concepts
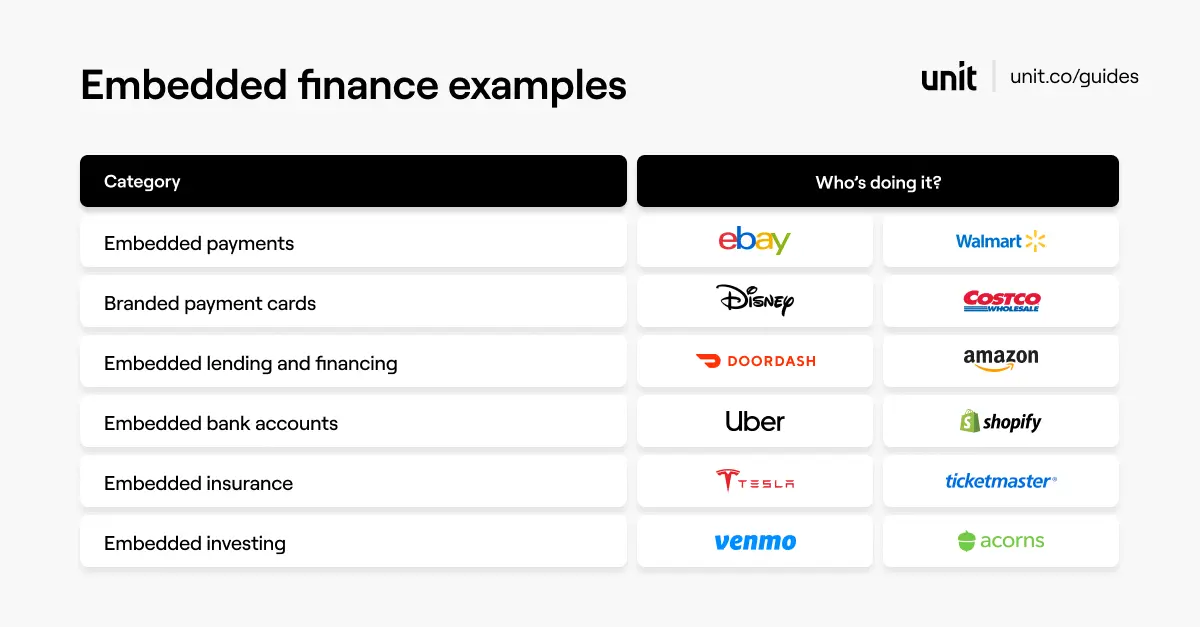
Seeing these ideas in action helps cement the theory. Below are three illustrative cases, each highlighting a different angle of the IPSE/Embedded SE spectrum.
1. Marketplace‑Style E‑Commerce Platform
A mid‑size online marketplace wanted to keep sellers on its site rather than redirect them to external checkout pages. By integrating an IPSE solution, the marketplace offered instant payouts, multi‑currency support, and fraud protection—all under its own brand. The result? A 12% lift in completed sales and a lower cart‑abandonment rate, because shoppers never left the familiar interface.
2. Ride‑Sharing App Adding Micro‑Loans
A ride‑sharing company noticed many drivers struggled with vehicle financing. Through an Embedded SE partnership, it began offering short‑term micro‑loans directly in the driver app. The loan terms were displayed alongside earnings, and approval was instant thanks to real‑time ride data. Within six months, over 4,000 drivers accessed credit, and the app’s driver‑retention metric improved by roughly 8%.
3. SaaS Project‑Management Tool Providing Insurance
A SaaS provider for freelancers introduced liability insurance as an add‑on. Using an Embedded SE model, the insurer’s underwriting engine accessed project‑budget data to price policies on the fly. Users could toggle the coverage on a single settings page, and the premium was deducted automatically from their subscription invoice. The uptake was modest—about 5% of active users—but the average revenue per user (ARPU) rose by 3% without any extra marketing spend.
Practical Steps to Apply These Models
If you’re contemplating an embedded financial offering, follow this short roadmap to keep the project manageable.
- Identify the friction point: Look for a moment in your user journey where money moves, risk is assessed, or a guarantee would reassure the customer.
- Choose the right partner: For pure payments, a licensed IPSE provider with robust APIs is ideal. If you need credit or insurance, seek an Embedded SE platform that already supports those verticals.
- Map compliance responsibilities: Clarify which party handles KYC, AML, and data protection. A clear split prevents costly regulatory surprises later.
- Prototype the UI: Show the financial service as a natural extension of your product. Minimal clicks, consistent branding, and clear disclosures are non‑negotiable.
- Run a pilot: Start with a small user segment, monitor conversion, default rates, and user sentiment. Iterate before a full rollout.
Remember, the goal isn’t to become a bank overnight. It’s to augment your core value proposition with financial tools that make life easier for your users—and, incidentally, boost your own margins.
FAQ
What’s the biggest regulatory risk when embedding finance?
Usually it’s assuming the host can sidestep licensing requirements. Even with an IPSE partner, you may still be liable for consumer protection laws if you market the service under your brand.
Can a small startup afford an Embedded SE solution?
Many providers offer revenue‑share models, so you pay only when a transaction occurs. That lowers upfront costs and aligns incentives.
How do I measure success beyond simple transaction volume?
Track metrics like churn reduction, ARPU uplift, and cross‑sell rates. These show the broader impact of embedding finance on your business health.
Is it possible to combine IPSE and other embedded services?
Absolutely. A platform might use IPSE for checkout while simultaneously offering credit or insurance through separate Embedded SE partners, creating a cohesive financial ecosystem.