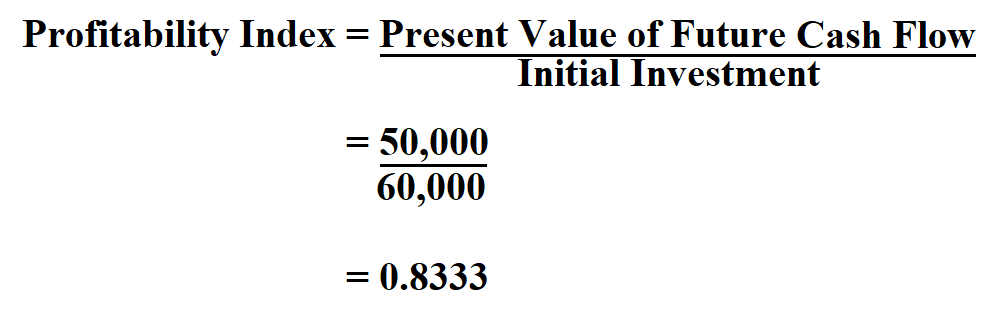How to Calculate the Profitability Index (Formula Explained)
Understanding the Profitability Index Formula
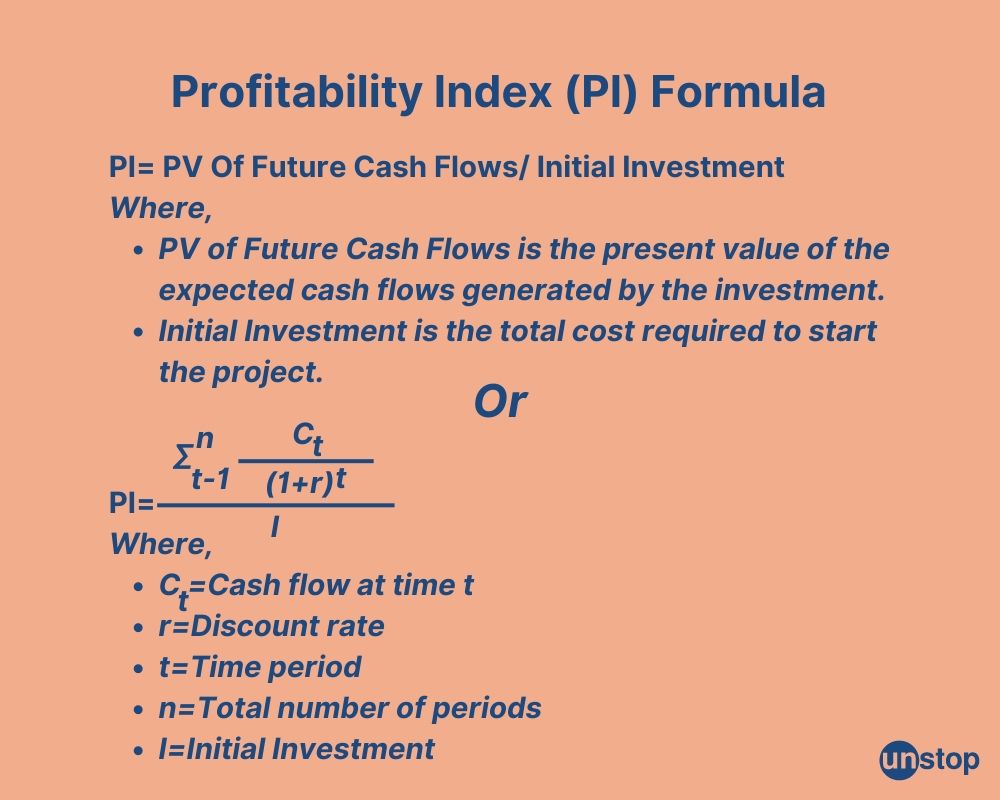
The profitability index (PI) is a simple yet powerful tool for evaluating investment projects. It compares the present value of future cash flows to the initial outlay, giving decision‑makers a single number that reflects value creation per unit of cost. In practice, a PI greater than 1 signals a project that should, in theory, add net wealth, while a value below 1 warns of potential loss. Grasping the formula behind this ratio is the first step toward using it confidently.
Step‑by‑Step Calculation Guide
Calculating the profitability index follows a straightforward sequence, but each step deserves attention to avoid common pitfalls. Below is a practical roadmap that works whether you’re assessing a small equipment purchase or a multi‑year infrastructure plan.
- 1. Estimate future cash flows. Project all expected inflows (revenues, savings, salvage) for each period the investment will generate benefits. Include realistic assumptions about growth, market conditions, and operational costs.
- 2. Choose an appropriate discount rate. This rate reflects the opportunity cost of capital—often the firm’s weighted average cost of capital (WACC) or a hurdle rate set by senior management.
- 3. Discount each cash flow. Apply the present value formula PV = CF / (1 + r)^t, where CF is the cash flow for year t and r is the discount rate.
- 4. Sum the discounted cash flows. The total represents the present value of benefits (PVB).
- 5. Identify the initial investment. This is the cash outflow at time zero, often denoted as I₀.
- 6. Apply the profitability index formula.
PI = PVB / I₀
When you plug the numbers in, the result instantly tells you whether the project’s benefits outweigh its costs when both are expressed in today’s dollars.
Interpreting the Result: What Does a PI Tell You?
A PI of 1.25, for example, means that for every dollar invested you expect to receive $1.25 in present‑value terms—a 25 % upside. Conversely, a PI of 0.92 suggests you’ll get back only $0.92 per dollar spent, indicating a net loss if the firm adheres strictly to the discount rate used.
However, the index should never be the sole criterion. It ignores project scale, strategic fit, and risk nuances that might make a lower‑PI project attractive—such as entering a new market or complying with regulation. Use the PI alongside other metrics like net present value (NPV) and internal rate of return (IRR) for a balanced view.
Common Mistakes and How to Avoid Them
Even seasoned analysts can slip up. Here are three frequent errors and practical ways to sidestep them:
- Skipping the discounting step. Treating nominal cash flows as if they were already in present value inflates the PI and creates a false sense of profitability.
- Using an inconsistent discount rate. Switching between the firm’s WACC and a project‑specific hurdle rate without justification skews the comparison and may overstate or understate the index.
- Overlooking salvage value. The terminal cash flow—often a residual asset sale—should be discounted like any other period. Ignoring it reduces the numerator and can turn a viable project into a borderline case.
When the Profitability Index Shines
The PI is especially handy when capital is constrained. Imagine a company with a fixed budget that must rank multiple projects. By ordering proposals from highest to lowest PI, managers can allocate funds to the most value‑dense opportunities until the budget is exhausted.
It also works well for public‑sector decisions where the goal is to maximize social welfare per dollar spent. Because the index normalizes benefits by cost, it facilitates comparisons across projects of wildly different sizes.
Real‑World Example
Suppose a manufacturing firm is evaluating a new production line that costs $5 million. Projected cash inflows over five years are $2 million, $2.5 million, $3 million, $3.5 million, and $4 million. Using a discount rate of 8 %:
- PV of year‑1 cash flow = 2 M / (1.08)^1 ≈ $1.85 M
- PV of year‑2 cash flow = 2.5 M / (1.08)^2 ≈ $2.14 M
- PV of year‑3 cash flow = 3 M / (1.08)^3 ≈ $2.38 M
- PV of year‑4 cash flow = 3.5 M / (1.08)^4 ≈ $2.59 M
- PV of year‑5 cash flow = 4 M / (1.08)^5 ≈ $2.73 M
Summing these gives a total present value of benefits around $11.69 million. The profitability index is then 11.69 / 5 ≈ 2.34. Since the PI exceeds 1 by a comfortable margin, the project appears financially sound.
Integrating PI Into a Decision Framework
While the PI offers clarity, embedding it within a broader analytical structure ensures you capture strategic considerations. A typical workflow might look like this:
- Screen projects using quick metrics (PI, IRR).
- Perform a detailed NPV analysis for the top candidates.
- Run sensitivity tests on discount rates, cash‑flow assumptions, and salvage values.
- Assess non‑financial factors—regulatory compliance, brand impact, and resource constraints.
- Finalize the portfolio based on a mix of quantitative scores and qualitative judgments.
This layered approach reduces the risk of over‑reliance on any single number, including the profitability index.
FAQ
What discount rate should I use for the profitability index?
Typically, firms apply their weighted average cost of capital (WACC) as the discount rate, but project‑specific risk premiums can be added when the investment’s risk profile deviates significantly from the company’s overall risk.
Can the profitability index handle projects with unequal lifespans?
Yes, but you must compare each project over a common horizon—often the longest project’s life—or adjust cash flows using a terminal value that captures the residual benefits beyond the shorter project’s timeframe.
Is a higher PI always better than a lower one?
Higher is generally preferable, yet a lower PI might still be chosen if the project delivers strategic advantages, satisfies regulatory requirements, or serves as a stepping stone toward larger, more profitable initiatives.
How does the profitability index differ from the benefit‑cost ratio?
They are mathematically identical; the term “profitability index” is more common in corporate finance, while “benefit‑cost ratio” appears in public‑sector and environmental economics. Both compare discounted benefits to discounted costs.