How Tesla’s Debt‑to‑Equity Ratio Could Look in 2025
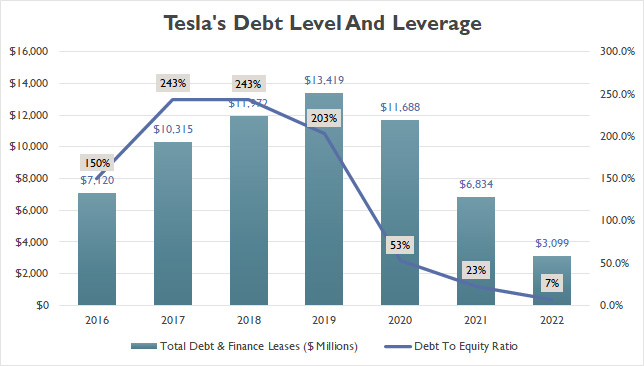
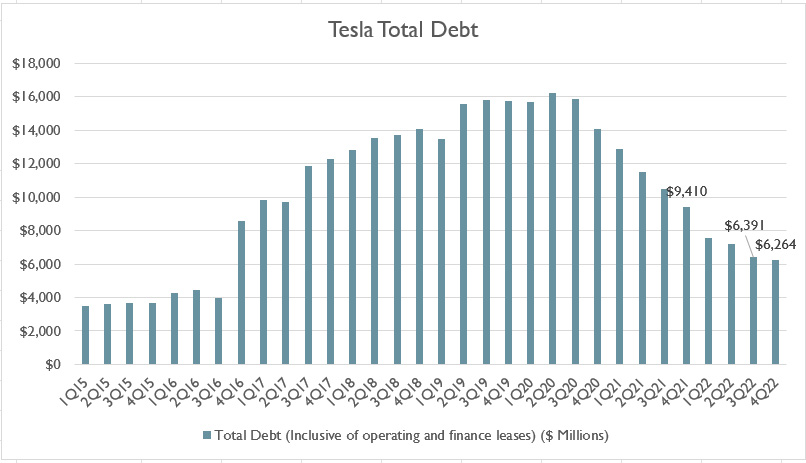
Investors who watch Tesla’s balance sheet know that the debt‑to‑equity (D/E) ratio is a quick litmus test for financial risk. With the company gearing up for new factories, battery breakthroughs, and expanding autonomous‑driving services, analysts are already projecting what the D/E ratio might be by 2025. This guide walks through the numbers, the forces that could shift them, and what a higher or lower ratio would mean for shareholders.
What the Debt‑to‑Equity Ratio Actually Measures
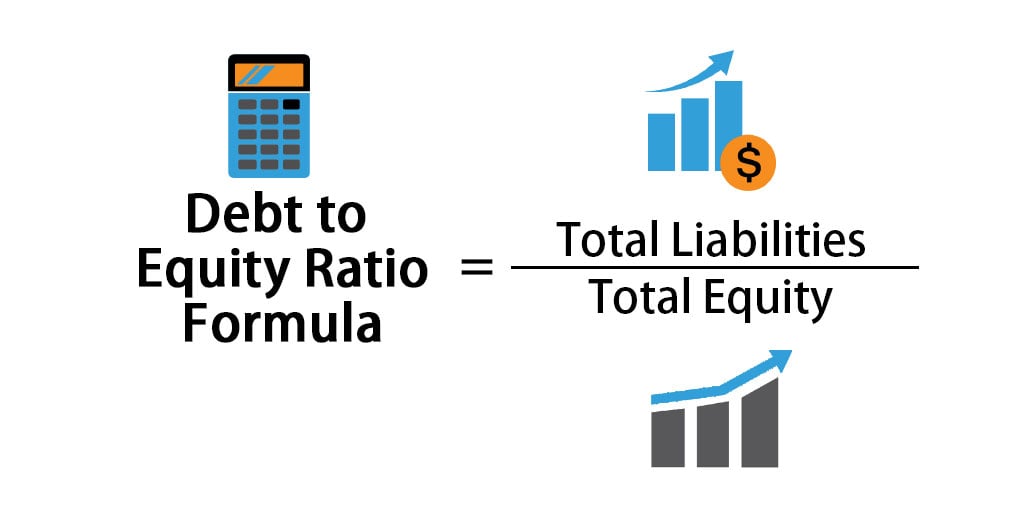
Simply put, the D/E ratio compares a firm’s total debt to its shareholders’ equity. A ratio of 1.0 means the company owes as much as it owns; a higher figure signals greater reliance on borrowed money, while a lower figure suggests a stronger equity cushion. For a capital‑intensive player like Tesla, the ratio is a balancing act between funding rapid growth and maintaining fiscal stability.
Tesla’s Debt‑to‑Equity Ratio Forecast for 2025
Based on the latest quarterly filings and forward‑looking statements from management, most mid‑year 2024 forecasts place Tesla’s 2025 D/E ratio somewhere between 0.5 and 0.9. The spread reflects uncertainty around three main variables: upcoming debt issuances, projected earnings, and the pace of capital spending on new gigafactories.
Key Drivers That Could Push the Ratio Higher
- New factory financing. The Berlin and Texas plants are still under construction, and Tesla may tap the bond market to close the gap.
- Battery‑technology investments. Scaling the 4680 cell production line could require sizable loans or revolving credit facilities.
- Interest‑rate environment. If the Federal Reserve keeps rates elevated, borrowing costs rise, prompting the company to lock in longer‑term debt now.
Factors Likely to Keep the Ratio Low
- Strong cash flow. Tesla’s operating cash flow has consistently outpaced its capital expenditures, leaving room to repay existing debt.
- Equity inflows. Recent secondary offerings and the potential for a modest share buyback can bolster equity, diluting the impact of debt.
- Revenue growth. Aggressive sales of Model Y, Cybertruck pre‑orders, and expanding software subscriptions add to the equity base.
Scenario Analysis: Best‑Case, Base‑Case, and Worst‑Case
Best‑case. If Tesla’s 2024 earnings per share exceed consensus by a comfortable margin and the company avoids any major debt issuances, the D/E ratio could dip below 0.5. That would signal a very strong balance sheet, potentially encouraging higher valuation multiples.
Base‑case. In the most likely scenario, Tesla raises $5‑$7 billion in green bonds to fund its gigafactory pipeline while maintaining robust cash flow. The D/E ratio would settle around 0.7, a level still comfortable for a growth‑focused automaker.
Worst‑case. Should the global economy slip into a recession, vehicle demand could soften, prompting Tesla to lean on additional credit lines. A D/E ratio creeping toward 0.9 would raise eyebrows but would not be unprecedented for a company in a capital‑heavy expansion phase.
How the Ratio Affects Investors
When the D/E ratio climbs, bondholders may demand higher yields, and equity investors could see a modest increase in perceived risk. Conversely, a falling ratio often translates into lower financing costs and can free up cash for dividends or share repurchases—though Tesla has never paid a dividend, it does occasionally buy back stock.
It’s also worth noting that the D/E ratio alone doesn’t tell the whole story. Analysts typically pair it with metrics like interest coverage, free cash flow conversion, and return on invested capital to gauge whether debt is being used efficiently.
Practical Tips for Monitoring Tesla’s Leverage
Stay on top of quarterly earnings releases and the accompanying MD&A section, where Tesla’s CFO outlines debt strategy. Look for changes in the “long‑term debt” line item, as well as any commentary about upcoming bond issuances. Finally, keep an eye on the broader EV market: supply‑chain bottlenecks or policy shifts (e.g., new tax credits) can quickly alter cash flow expectations.
Quick FAQ
Q: Is a D/E ratio above 1.0 dangerous for Tesla?
A: Not necessarily. While a ratio above 1.0 signals more debt than equity, Tesla’s strong cash flow and growth outlook can offset the risk. Investors should look at the trend and the company’s ability to service debt rather than the raw number alone.
Q: Could Tesla’s D/E ratio improve without raising equity?
A: Yes. If operating cash flow consistently exceeds capital expenditures, Tesla can use excess cash to pay down debt, which would lower the ratio even without issuing new shares.
Q: How does Tesla’s D/E ratio compare to traditional automakers?
A: Legacy manufacturers like Ford and General Motors typically carry ratios around 1.2‑1.5, reflecting older, debt‑heavy business models. Tesla’s projected sub‑1.0 range would position it as less leveraged than many peers.
Q: Should I adjust my Tesla position based on the D/E forecast?
A: The ratio is just one piece of the puzzle. Consider overall valuation, growth prospects, and competitive dynamics alongside leverage before making a decision.