How Prodigy Finance Simplifies Overseas Education Loans
Securing financing for a degree abroad can feel like navigating a maze of paperwork, credit checks, and currency conversions. Overseas education loans are designed to bridge that gap, but not all lenders speak the language of international students. Enter Prodigy Finance, a fintech platform that tailors its products to the unique challenges faced by scholars chasing degrees in places like the UK, US, or Australia. This guide walks through what you need to know before you click “apply.”
What Are Overseas Education Loans and Why Choose Prodigy Finance?
In essence, an overseas education loan is a credit facility that covers tuition, living expenses, and sometimes even travel costs for students studying outside their home country. Traditional banks often demand a local co‑signer, a solid credit history, or collateral—requirements that can be tough for a recent graduate. Prodigy Finance sidesteps many of these hurdles by evaluating applicants based on future earning potential, the reputation of the chosen university, and the field of study.
Eligibility Criteria
While each loan program varies slightly, the core eligibility guidelines are fairly consistent:
- Admission to a participating graduate or postgraduate program at a recognized institution.
- Citizenship or permanent residency in one of the supported home countries (over 150 nations are covered).
- Demonstrated ability to repay, usually measured through projected salaries in the chosen career path.
- Minimum academic performance—most programs expect a GPA of 3.0 or higher.
Notably, a credit score from your home country isn’t a deal‑breaker, which opens doors for high‑potential students who haven’t yet built a credit history.
How the Application Works
The process is deliberately digital. After creating an account on Prodigy’s website, you’ll upload your acceptance letter, passport, and a few financial documents. An algorithm—supplemented by human underwriters—reviews the data and typically returns a decision within two weeks. If approved, funds are disbursed directly to the university in the local currency, and you’ll receive a repayment schedule that aligns with the start of your post‑graduation salary.
Key Benefits
Choosing Prodigy Finance comes with several perks that resonate with globetrotting scholars:
- No collateral or cosigner required. Your future earnings become the security.
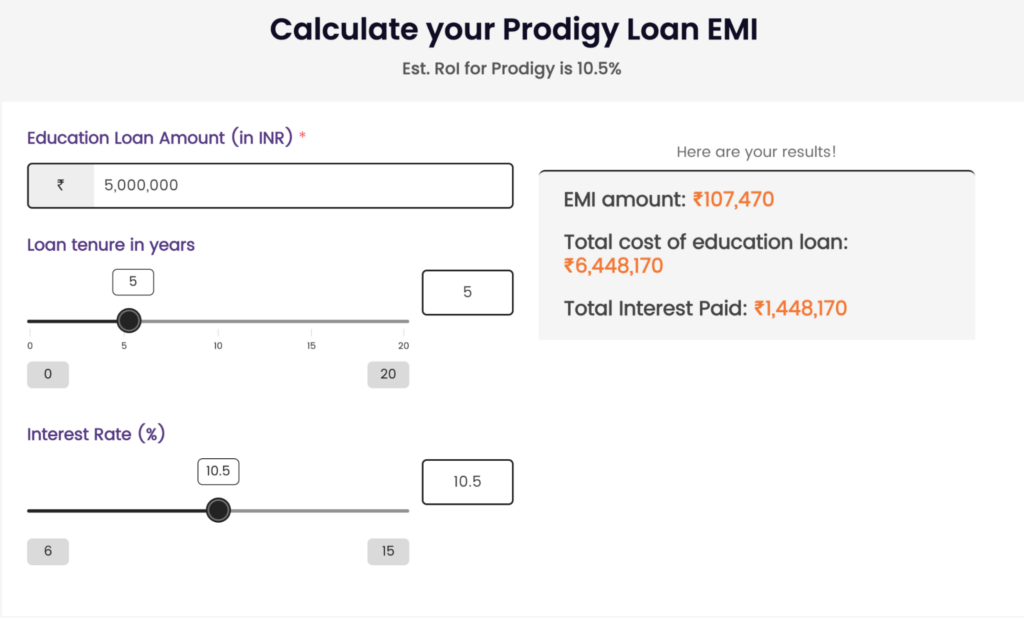
- Competitive interest rates that are often lower than those of private lenders, especially for high‑demand fields like engineering and finance.
- Flexible repayment terms, including a grace period that lets you focus on studies before the first payment.
- Dedicated support teams familiar with visa timelines, tuition fee structures, and local banking quirks.
Potential Drawbacks
Nothing is perfect, and Prodigy Finance has its own set of considerations. First, the platform primarily serves postgraduate programs; undergraduate students may need to look elsewhere. Second, while interest rates are competitive, they can still be higher than rates offered by some government‑backed schemes in your home country. Finally, the loan amount is capped at a percentage of tuition—usually up to 100% of tuition plus a modest allowance for living costs—so you’ll need to budget any additional expenses.
Comparing Prodigy Finance with Traditional Bank Loans
If you’re weighing options, the contrast becomes clearer when you line up the main factors side by side.
- Credit requirements: Banks often need a local credit score or a guarantor; Prodigy looks at future salary potential.
- Application speed: Bank loans can take months, while Prodigy’s digital workflow aims for a two‑week turnaround.
- Currency handling: Traditional lenders may disburse in your home currency, exposing you to exchange‑rate risk. Prodigy pays the university directly in the local currency, eliminating that variable.
- Repayment flexibility: Most banks start repayment immediately; Prodigy typically offers a grace period until you graduate and secure a job.
That said, if you already have strong ties to a local bank, a low‑interest personal loan might still beat Prodigy’s rates. The right choice hinges on your citizenship, credit background, and the specific program you’re attending.
Tips for Getting the Most Out of Your Loan
Even a well‑designed loan can be optimized. Here are a few practical suggestions:
- Lock in the rate early. Interest rates can fluctuate, so applying as soon as you receive your acceptance letter helps you secure the advertised rate.
- Factor in the grace period. Use it to line up part‑time work or internships that will boost your post‑graduation salary.
- Keep an eye on exchange‑rate trends. While Prodigy pays the school directly, any additional personal expenses you cover in your home currency will be affected by market moves.
- Consider pre‑payment options. Some lenders charge penalties for early repayment; Prodigy generally allows extra payments without fees, which can shave years off the term.
Frequently Asked Questions
Can I use a Prodigy Finance loan for undergraduate studies?
Currently, Prodigy focuses on master’s, MBA, and PhD programs. Undergraduate applicants need to explore alternative lenders or scholarship opportunities.
What happens if I can’t find a job after graduation?
Prodigy builds a repayment plan based on projected earnings, but if you face a prolonged job search, you can request a temporary deferment. The platform’s support team works with you to adjust the schedule without immediate penalties.
Are there any hidden fees?
The loan agreement lists a processing fee—usually a small percentage of the total amount—plus the standard interest. There are no surprise charges for early repayment or currency conversion.
Do I need a visa to qualify?
A valid student visa for the destination country is part of the required documentation. Prodigy verifies your visa status before disbursing funds, ensuring compliance with both host‑country regulations and its own lending policies.