How NatWest Business Car Finance Works: A Practical Guide
If you’re a small‑to‑mid‑size firm looking to add a reliable vehicle to your fleet, chances are you’ve already heard of NatWest Business Car Finance. It’s a financing solution that lets you spread the cost of a new or used car over several years while keeping ownership flexible. In this guide we’ll demystify the key elements, walk through the application steps, and flag the hidden costs you should keep an eye on.
What Is Business Car Finance?
At its core, business car finance is a loan‑like arrangement where a lender pays the full purchase price of a vehicle and you repay the amount – plus interest – over an agreed term. Unlike a personal loan, the vehicle is tied to your business’s credit profile, and the repayments are usually treated as a deductible business expense. This structure helps preserve cash flow, especially when you need a car for client visits, deliveries, or sales calls.
Why Choose NatWest for Your Fleet
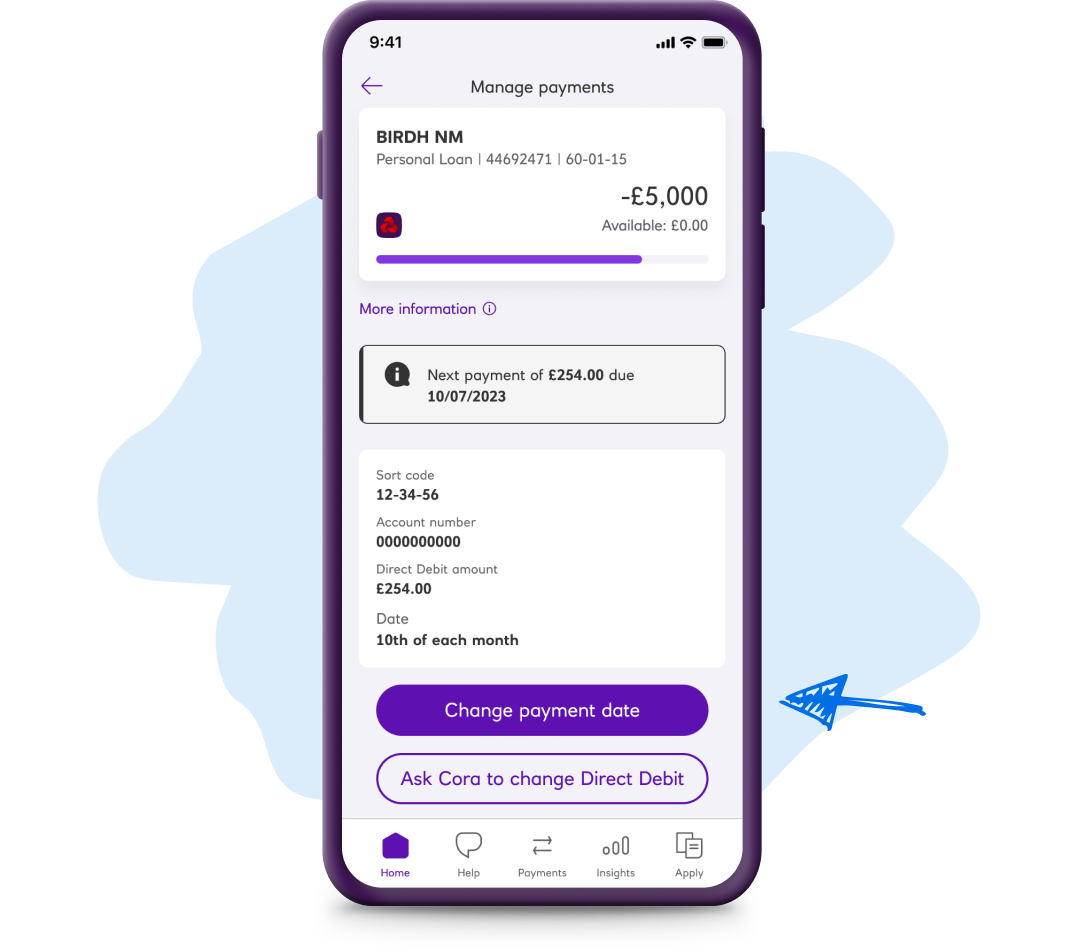
NatWest is one of the UK’s biggest high‑street banks, and its business division offers a few perks that make it worth a closer look. First, the bank leverages its extensive credit‑assessment tools, which can mean more competitive rates for well‑run companies. Second, NatWest bundles its financing with optional services like maintenance packages and insurance add‑ons, streamlining what would otherwise be separate contracts. Finally, the online portal gives you real‑time visibility into outstanding balances and upcoming payment dates.
Key Features of NatWest Business Car Finance
- Flexible terms – Contracts range from 12 to 60 months, allowing you to match repayments with your revenue cycle.
- Deposit options – You can put down as little as 10 % of the vehicle price, though a larger deposit typically secures a lower APR.
- Mileage allowances – NatWest offers both unlimited mileage and capped‑kilometre plans, depending on the vehicle type.
- Early repayment – There’s usually an option to settle the agreement early, though a modest exit fee may apply.
- Tax efficiency – Payments can be recorded as operating expenses, which may reduce your corporation tax liability.
How the Application Process Unfolds
Applying for NatWest Business Car Finance is a three‑step affair. First, you’ll need to gather basic documentation: your company’s registration number, recent bank statements, and a projected cash‑flow forecast. Second, an online form asks for details about the vehicle you intend to purchase – make, model, price, and whether it’s new or used. Finally, a NatWest credit officer reviews the submission, often reaching out for clarifications, before issuing a conditional approval within a week.
Costs and Terms to Watch
Interest rates are not one‑size‑fits‑all; they hinge on your business’s credit score, the loan‑to‑value ratio, and the length of the term. Typically, APRs hover between 4 % and 9 % for established firms, but newcomers may see higher rates. Keep an eye on the “balloon payment” clause – some agreements let you defer a larger lump sum to the end of the term, which can be handy for cash‑flow but adds risk if the business slows down. Also, read the fine print on excess‑mileage charges; they can add up quickly if you exceed the agreed limit.
Managing Your Finance Agreement
Once the deal is signed, the real work begins. Set up automated payments through NatWest’s business banking portal to avoid missed deadlines. Schedule regular service appointments if you’ve opted for a maintenance package – this not only preserves the car’s resale value but also helps you stay within the agreement’s condition requirements. If you anticipate a change in usage patterns, contact NatWest early to renegotiate mileage limits or term extensions; proactive communication often prevents surprise fees.
Common Pitfalls and How to Avoid Them
Many entrepreneurs make the mistake of underestimating total ownership costs. Beyond the monthly repayment, factor in insurance, fuel, and routine servicing. Another frequent slip‑up is overlooking the early‑termination fee – if your business pivots and you need to sell the vehicle, that fee can erode any savings from an early payoff. Lastly, be wary of “too good to be true” promotional rates; they sometimes come with restrictive clauses that limit vehicle choice or require a higher deposit later on.
FAQ
- Can I finance a used car through NatWest Business Car Finance? Yes, the program accepts both new and pre‑owned vehicles, though the interest rate may be slightly higher for used cars due to depreciation concerns.
- What credit score does NatWest look for? While there’s no fixed threshold, a business credit rating of “Good” (typically 70 % or above on standard scoring models) improves your chances of securing a lower APR.
- Is there a mileage limit on the finance agreement? NatWest offers both unlimited mileage options and capped‑kilometre plans. Unlimited mileage usually carries a marginally higher rate, but it eliminates the risk of excess‑kilometre charges.
Choosing the right financing partner can feel like a gamble, but with NatWest’s transparent terms and supportive online tools, you gain a clearer picture of what each payment truly means for your bottom line. Take the time to compare a few quotes, run the numbers on total cost of ownership, and you’ll drive your business forward with confidence.