How Indonesia’s Steel Exports Are Becoming a Global Power
Why Indonesia’s Steel Sector Is Suddenly on Everyone’s Radar
Over the past decade, Indonesia has moved from a modest regional supplier to a contender that can shape global steel dynamics. The country’s export figures, once eclipsed by heavyweight producers like China and India, now register steady double‑digit growth, catching the eye of analysts and buyers alike.
Indonesia’s Steel Exports: A Snapshot of Recent Growth
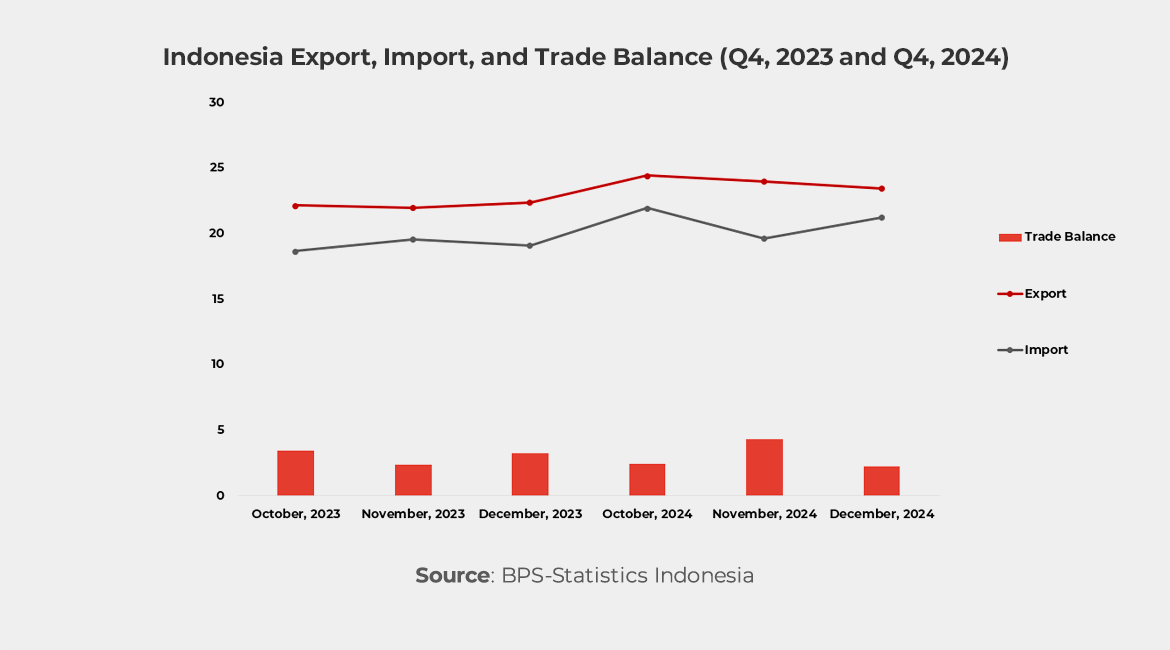
In the last few years, Indonesia’s steel export volume has risen by roughly fifteen percent year‑over‑year, while the value of those shipments has climbed even faster thanks to a shift toward higher‑margin products such as galvanized coils and cold‑rolled sheets. This upward trend reflects not only increased capacity but also a deliberate pivot toward markets that reward quality and consistency over sheer volume.
Key Drivers Behind the Export Surge
Several forces converge to push Indonesia’s steel onto the world stage:
- Newly commissioned plants. The construction of integrated steel complexes in East Java and South Sumatra has added millions of tonnes of annual capacity.
- Government incentives. Tax breaks and streamlined licensing encourage both foreign investors and local firms to expand their export‑ready lines.
- Competitive labor costs. While wages have risen modestly, they remain lower than in many neighboring economies, keeping production costs attractive.
- Strategic port infrastructure. Upgrades at Tanjung Priok and Belawan enable larger vessels to dock, reducing shipping expenses.
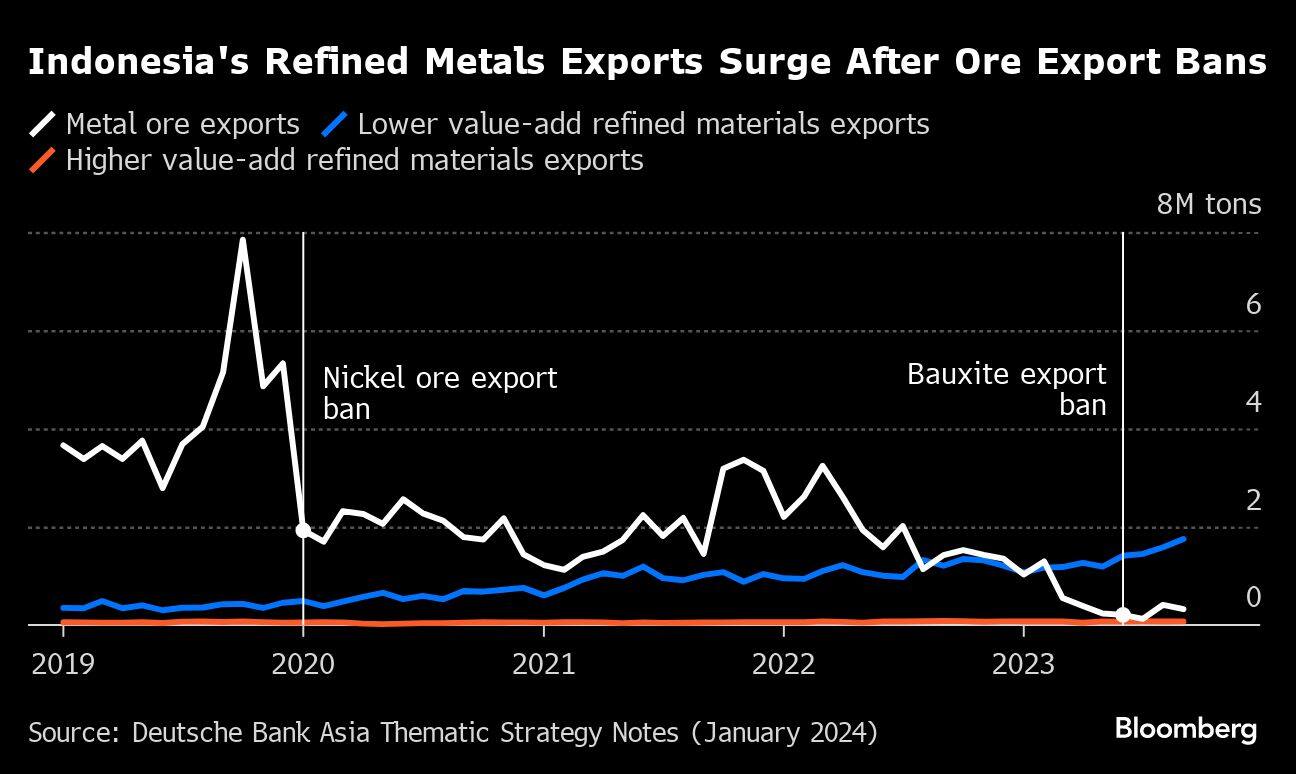
- Domestic demand plateau. As Indonesia’s own construction boom eases, producers look outward for growth, turning excess capacity into export opportunities.
Main Destination Markets
Indonesia’s steel now sails to a diverse set of buyers. Southeast Asian neighbors—especially Vietnam, the Philippines, and Thailand—remain the top volume recipients, thanks to shared supply chains and similar product specifications. Beyond the region, the Middle East has emerged as a lucrative market for corrosion‑resistant steel used in oil‑and‑gas infrastructure, while African nations such as Kenya and Nigeria import Indonesian rebar to support fast‑growing urban projects.
Challenges That Could Temper Growth
Despite the optimism, several headwinds loom. Environmental regulations are tightening, and newer plants must invest in cleaner technologies to meet both domestic law and the expectations of eco‑conscious importers. Currency fluctuations also pose a risk; a stronger rupiah can erode price competitiveness. Finally, the global steel market remains sensitive to trade policies—tariffs imposed by major economies could quickly redirect cargoes elsewhere.
What the Future Might Hold
Looking ahead, the consensus among industry observers is that Indonesia will continue to carve out a niche in specialized steel products rather than attempting to out‑produce the giants. Investment in advanced rolling mills and value‑added processing—such as high‑strength automotive steel—could secure higher profit margins and deepen relationships with overseas manufacturers.
At the same time, the nation’s push toward digitalization, including real‑time supply‑chain tracking and automated quality control, promises to boost reliability—a factor that matters increasingly to global buyers who demand transparency and consistency.
Frequently Asked Questions
Which countries import the most Indonesian steel?
Vietnam, the Philippines, Thailand, and Malaysia lead in volume, while the United Arab Emirates and Saudi Arabia top the list for higher‑value, corrosion‑resistant grades.
How has Indonesia’s steel production capacity changed recently?
Since 2018, the country has added roughly five million tonnes of annual capacity, primarily through new integrated plants and the expansion of existing rolling mills.
What role does the government play in supporting steel exports?
Policy measures include tax holidays for export‑oriented projects, subsidies for energy‑efficient equipment, and investments in port upgrades that lower logistical bottlenecks.