Financial Ratio Analysis: A Complete Guide to Smarter Decisions
Why Financial Ratios Matter
When you stare at a balance sheet or income statement, numbers can feel abstract. Financial ratio analysis turns those raw figures into a story about a company’s health, efficiency, and risk. Investors, lenders, and managers all lean on ratios to spot trends that raw data hides. In short, ratios give you a shortcut to answering “Is this business performing well?” without drowning in spreadsheets.
Getting Started: The Core Categories
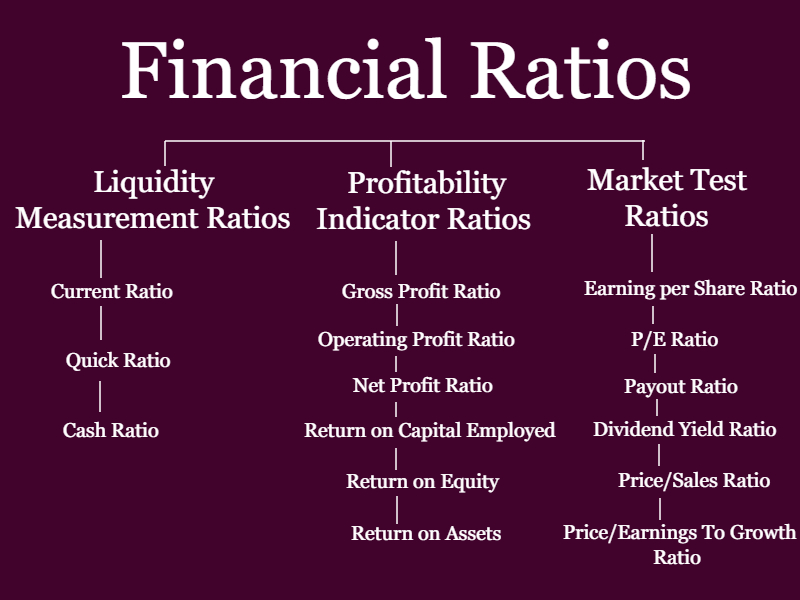
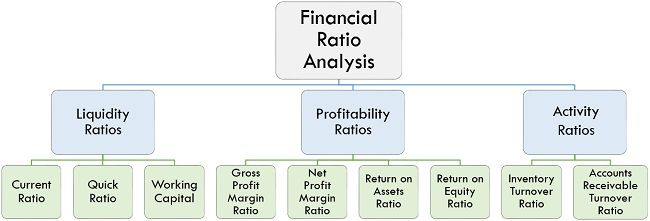
Most analysts group ratios into four buckets: profitability, liquidity, leverage, and efficiency. Each bucket answers a different question about the firm.
- Profitability ratios gauge how much profit a company generates relative to sales, assets, or equity.
- Liquidity ratios measure the ability to meet short‑term obligations.
- Leverage ratios reveal the extent of debt financing.
- Efficiency (or activity) ratios show how well resources are turned into revenue.
Understanding these categories helps you choose the right metrics for the problem at hand.
Key Profitability Ratios and How to Use Them
Gross Profit Margin
Gross profit margin = (Revenue – Cost of Goods Sold) ÷ Revenue. It tells you how much of each sales dollar remains after covering production costs. A rising margin often signals pricing power or cost‑control improvements.
Operating Margin
Operating margin = Operating Income ÷ Revenue. This ratio adds back overhead and administrative expenses, giving a clearer picture of core business performance. If operating margin lags behind gross margin, look for inefficiencies in sales, marketing, or admin functions.
Return on Equity (ROE)
ROE = Net Income ÷ Shareholder’s Equity. Investors love a high ROE because it reflects how effectively capital is being turned into profit. However, an unusually high ROE can sometimes hide excessive leverage, so pair it with a leverage metric.
Liquidity Ratios: The Safety Net
Current Ratio
Current ratio = Current Assets ÷ Current Liabilities. A ratio above 1 suggests the company can cover its short‑term debts. Too high a ratio might indicate excess cash sitting idle, while a ratio below 1 raises red flags.
Quick Ratio (Acid‑Test)
Quick ratio = (Cash + Marketable Securities + Accounts Receivable) ÷ Current Liabilities. By stripping out inventory, this measure focuses on the most liquid assets, offering a stricter test of short‑term solvency.
Leverage Ratios: Debt’s Double‑Edged Sword
Debt‑to‑Equity Ratio
Debt‑to‑Equity = Total Debt ÷ Shareholder’s Equity. This ratio compares borrowed capital to owners’ capital. A moderate level can boost returns, but high levels increase default risk, especially when earnings are volatile.
Interest Coverage Ratio
Interest coverage = EBIT ÷ Interest Expense. It shows how many times a company can cover its interest payments with operating earnings. Ratios under 1.5 often trouble lenders; ratios above 3 are generally comfortable.
Efficiency Ratios: Turning Assets into Revenue
Inventory Turnover
Inventory turnover = Cost of Goods Sold ÷ Average Inventory. A high turnover indicates fast moving stock, which reduces holding costs. Conversely, a low turnover may point to obsolete inventory or weak demand.
Asset Turnover
Asset turnover = Revenue ÷ Average Total Assets. This metric reveals how efficiently a firm uses its asset base to generate sales. Capital‑intensive industries typically have lower asset turnover than service‑oriented firms.
Putting It All Together: A Practical Workflow
1. Collect the numbers. Pull the latest balance sheet, income statement, and cash‑flow statement. Consistency matters—use the same period for all ratios.
2. Calculate the core set. Start with one ratio from each category (e.g., gross margin, current ratio, debt‑to‑equity, asset turnover). This gives a balanced snapshot.
3. Benchmark. Compare the results against industry averages, historical performance, or key competitors. Ratios only become meaningful in context.
4. Identify red flags. Look for outliers—sharp declines, unusually high leverage, or a liquidity ratio drifting below 1. Those are starting points for deeper analysis.
5. Drill down. If a profit margin is slipping, examine cost of goods sold and operating expenses. If the debt‑to‑equity ratio spikes, check the debt schedule for upcoming maturities.
6. Report findings. Summarize the story the ratios tell—strengths, weaknesses, and actionable recommendations. Use visual aids like trend graphs or radar charts to make the data intuitive.
Common Pitfalls to Avoid
Relying on a single ratio can be misleading. For example, a high ROE looks great until you discover it’s driven by a tiny equity base caused by heavy borrowing. Also, beware of seasonality; comparing quarterly ratios without adjusting for seasonal effects can paint a false picture.
Another trap is ignoring the quality of the underlying data. Restatements, aggressive accounting policies, or one‑off items can skew ratios. Whenever possible, use adjusted or normalized figures to smooth out anomalies.
FAQ
What is the best ratio for assessing a company’s profitability?
While no single ratio tells the whole story, many analysts start with gross profit margin to gauge core production efficiency, then move to operating margin and ROE for a fuller view.
How often should I update my ratio analysis?
Quarterly updates align with financial reporting cycles and allow you to spot trends early. For fast‑moving industries, monthly snapshots can be valuable, especially for liquidity and cash‑flow ratios.
Can financial ratios predict bankruptcy?
Certain ratios—like a declining interest coverage ratio combined with a rising debt‑to‑equity—are strong warning signs. However, ratios alone can’t predict failure; they should be part of a broader risk assessment that includes market conditions and management quality.
Do small businesses use the same ratios as large corporations?
The core concepts are identical, but small firms often focus more on cash‑flow–related metrics, such as the quick ratio, because they have less access to external financing.