Exploring Taxing Power: How Governments Exercise Authority
When we think of a government’s reach, the word that often surfaces is “taxing power.” Yet the concept extends far beyond the simple act of collecting revenue. It is the legal foundation that allows a state to shape economic behavior, fund public services, and uphold its social contract. This article walks through the historical roots, constitutional limits, and practical implications of taxing power, providing a clear lens on how governments wield this authority.
Taxing Power and the Limits of Government’s Authority
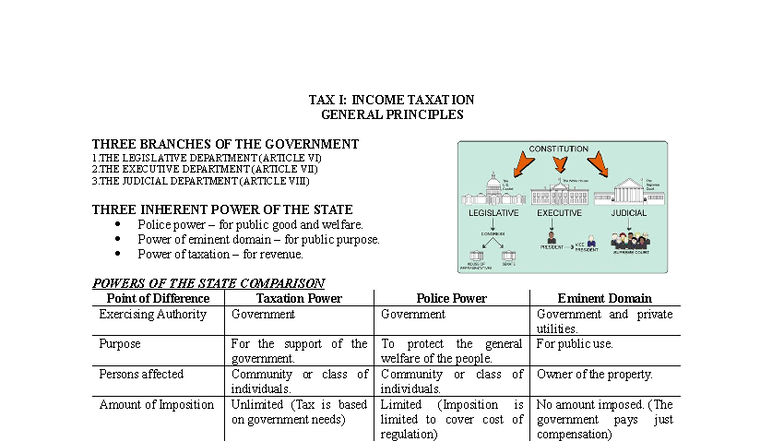
At its core, taxing power is an implicit grant of authority derived from the state’s sovereignty. Historically, the ability to tax has been a cornerstone of nation‑building, dating back to Roman taxation systems and evolving through feudal levies to modern welfare states. In many countries, the constitution explicitly recognizes this power, while also embedding checks to prevent abuse.
For example, the United States Constitution’s Article I, Section 8 lists the taxing authority as one of the federal powers. Simultaneously, the Taxing and Spending Clause in the same article sets a framework: “the Congress shall have power to lay and collect taxes, duties, imposts and excises.” Yet the phrase “and to provide for the general welfare” implies a purpose that must align with public benefit.
Constitutional Safeguards
- Due Process: Taxes cannot arbitrarily target individuals or businesses without a legal basis. Courts review whether a tax meets procedural and substantive due process requirements.
- Equal Protection: Tax policy must avoid discriminatory treatment unless justified by legitimate governmental interests.
- Separation of Powers: The legislature enacts tax law, the executive enforces it, and the judiciary interprets it—ensuring that no single branch can overstep its bounds.
Judicial Interpretation and the Role of the Courts
Courts often act as the final arbiters on whether a tax is constitutional. Landmark cases such as Gibbons v. Ogden and Marsh v. Alabama clarified that taxation must not be punitive beyond legitimate government purposes. More recent decisions, like National Federation of Independent Business v. Sebelius, examine the limits of federal authority when state interests intersect with national policy.
Fiscal Federalism and Intergovernmental Cooperation
In federations, taxing authority is divided among multiple levels of government. States may levy income, sales, or property taxes, but often rely on federal grants to balance budgets. These transfers are governed by formulas that consider population size, income levels, and cost of living, ensuring that lower‑income states can maintain essential services without excessive tax burdens.
Modern Challenges to Taxing Power
Globalization and technological advances have reshaped the taxation landscape. Multinational corporations now operate across borders, raising questions about how to attribute profits and enforce tax compliance. Digital services further blur the lines, as companies sell intangible products without a physical presence in many jurisdictions.
Countries are responding with international agreements—such as the OECD’s Base Erosion and Profit Shifting (BEPS) initiative—to standardize tax rules and reduce loopholes. Meanwhile, debates around “tax havens” and “tax avoidance” continue to drive reforms aimed at closing gaps that erode revenue streams.
The Public’s Role and Perception
Taxation is a public trust. Citizens expect transparency, fairness, and accountability. Transparency initiatives, like open budgeting portals and real‑time tax data, aim to demystify how tax dollars are spent. Public scrutiny also ensures that governments remain responsive to shifting needs—be it infrastructure investment, healthcare, or education.
In democratic societies, the electorate can influence tax policy through elections, referenda, and public campaigns. When tax burdens are perceived as inequitable, voters can push for reform, leading to changes such as progressive tax structures, wealth taxes, or carbon taxes aimed at addressing social and environmental concerns.
Practical Implications for Businesses and Individuals
Understanding your government’s taxing authority is vital for compliance and strategic planning. Here’s a quick cheat sheet for stakeholders:
- Businesses: Keep abreast of tax code updates, especially those related to digital services or cross‑border transactions. Engage in proactive tax planning to leverage deductions, credits, and incentives.
- Individuals: Familiarize yourself with income thresholds, deductions, and tax credits applicable in your jurisdiction. Use tax software or consult professionals to maximize legal savings.
- Non‑profits: Ensure that your tax-exempt status is maintained by adhering to reporting requirements and avoiding prohibited political activities.
In sum, taxing power is not just a fiscal tool—it is a reflection of a government's legitimacy, priorities, and commitment to its citizens. The balance between revenue generation and safeguarding individual rights remains a dynamic equilibrium, continually shaped by legal, economic, and societal forces.
FAQ
- What is taxing power? The legal authority granted to a government to levy taxes for public purposes.
- What limits the government's taxing authority? Constitutional provisions, judicial review, and principles such as due process and equal protection.
- Can a state tax beyond federal limits? States can impose taxes within their jurisdiction, but must comply with federal laws and any intergovernmental agreements.
- How does the Supreme Court check taxation? By evaluating whether a tax satisfies constitutional requirements and serves a legitimate governmental interest.