BRI Loan Requirements for Civil Servants: A Complete Guide
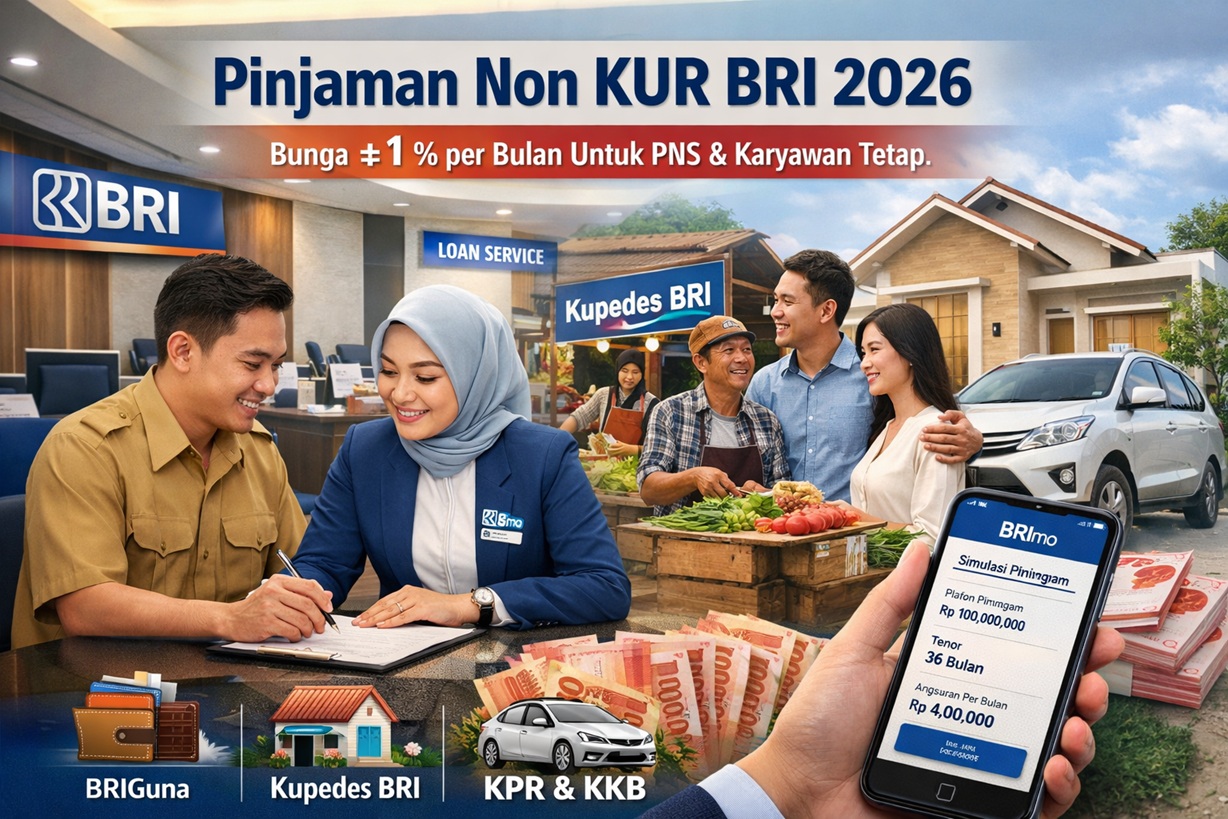
Bank Rakyat Indonesia (BRI) has long been a trusted financial partner for the nation's civil servants. Whether you’re a teacher, a municipal worker, or a civil engineer, BRI offers loan products tailored to the unique needs and steady income streams of public employees. This guide breaks down everything you need to know—from eligibility checks to document preparation—so you can secure the loan you want without the usual guesswork.
What Makes a BRI Loan Ideal for Civil Servants?
Unlike many commercial banks, BRI designs its loan terms around the predictable salary patterns of civil servants. Lower interest rates, flexible repayment periods, and generous collateral options are standard. Moreover, the bank’s “Pemerintah” (government) designation often results in a more streamlined approval process, especially when you’re a permanent staff member.
Core Eligibility Criteria
While BRI offers a variety of loan products, the most common for civil servants is the BRI Credit Loan (BriKredit). To qualify, you typically need:
- Official employment status (full‑time civil servant)
- At least one year of continuous service
- Regular salary deposit into a BRI account
- Good credit history (no significant defaults)
Some loan types, such as the “BRI Kartu Keluarga” or “BRI Pensiun,” have slightly different requirements, but the above criteria apply to most standard credit lines.
Essential Documents You Must Gather
Having all paperwork ready saves time and reduces back‑and‑forth. Commonly required documents include:
- Copy of your civil servant ID (KTP)
- Employment letter confirming status and salary
- Recent payslips (usually last three months)
- Bank statement showing regular deposits
- Property ownership deed or tenancy contract (if collateral is needed)
- Tax return or official income proof (for larger loan amounts)
BRI often accepts electronic versions, but you may need to provide hard copies during the final approval stage.
How to Apply: Online vs. Branch
BRI offers a seamless digital application via its mobile app or website. Steps for online applicants:
- Register or log in to the BRI app.
- Choose “Credit Loan” and select the civil‑servant‑specific product.
- Enter personal and financial details; upload scanned documents.
- Submit and wait for a quick assessment.
For those who prefer face‑to‑face, visiting a local branch is equally straightforward. A teller will guide you through the paper forms, verify your documents, and provide real‑time updates on your application status.
Common Pitfalls and How to Avoid Them
Even experienced borrowers can trip over these small missteps:
- Under‑reporting income—ensure your payslips match the salary stated on your employment letter.
- Missing collateral documentation—if the loan requires a guarantee, a proper deed or lease agreement is mandatory.
- Applying for a higher amount without adequate collateral—BRI strictly enforces loan-to‑value ratios.
- Failing to keep your account active—BRI often requires a minimum balance or regular deposits.
Double‑check each item before submitting to keep the process moving smoothly.
Tips for Faster Approval
- Maintain a good credit score. Regular timely repayments on any existing credit will reflect positively.
- Keep your account balance stable. BRI prefers accounts with consistent deposits to avoid liquidity concerns.
- Use the same BRI account for salary deposits. This streamlines verification.
- Respond quickly to follow‑up requests. A delayed reply can stall the entire process.
By following these guidelines, you can often see a decision within 48–72 hours, especially for standard loan amounts.
FAQ
Q: Do I need to be a BRI customer to apply for a loan?
A: Yes, most BRI loan products require an active BRI savings or checking account. If you’re not yet a customer, you can open one during the application process.
Q: Can I apply for a loan if I’m on leave or temporarily transferred?
A: Eligibility may depend on the duration and type of leave. Generally, a minimum of one year of continuous service is required, but special circumstances can be reviewed on a case‑by‑case basis.
Q: What happens if my application is rejected?
A: BRI will provide a brief explanation. Common reasons include incomplete documentation, insufficient collateral, or a negative credit history. You can address the issue and reapply after resolving the cited points.
Q: Is the loan interest rate fixed or variable?
A: Most BRI consumer loans have a fixed rate for the entire term, offering predictable repayments. However, certain loan packages may offer variable rates tied to the BRI interest index.
With the right preparation and an understanding of these key points, civil servants can confidently navigate the BRI loan application process and secure the funds they need for homes, vehicles, or education.