2023 MAGI Income Limits for Medicare: Quick Read Guide
When planning for Medicare, many people overlook how the Medicare Adjustment Income Limits (MAGI) can affect their coverage options and out‑of‑pocket costs. The Quick Read MAGI Medical Income Limits Explained (2023) gives a clear snapshot of the numbers, how they’re calculated, and why they matter for every beneficiary. In this concise overview, you’ll find the key figures, the logic behind them, and practical steps to keep your plan on track.
Quick Read MAGI Medical Income Limits Explained (2023)
MAGI, or Modified Adjusted Gross Income, is the income threshold used by the Centers for Medicare & Medicaid Services (CMS) to determine whether you qualify for premium subsidies, the Low‑Income Subsidy (LIS), or extra help for prescription drugs. The 2023 limits apply to the tax year 2022, as the Social Security Administration and CMS update these figures annually based on the national poverty line and inflation.
What Is MAGI and Why It Matters
- MAGI includes: all wages, salaries, and bonuses; interest, dividends, and capital gains; taxable Social Security benefits; and other income sources, minus specific deductions such as student loan interest, tuition, and certain retirement contributions.
- CMS uses MAGI to decide if you’re eligible for Premium Tax Credits (PTC), which lower the cost of Medicare Advantage or Part D plans.
- Eligibility for the Low‑Income Subsidy (LIS) or Extra Help is also based on MAGI, impacting monthly premiums, deductibles, and copayments.
2023 Income Thresholds for 2022
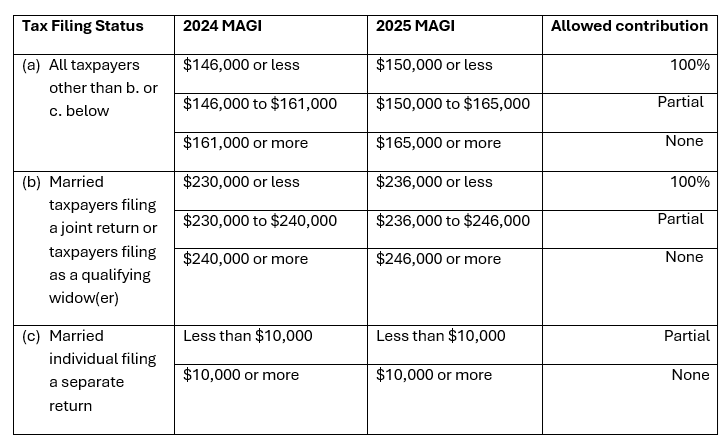
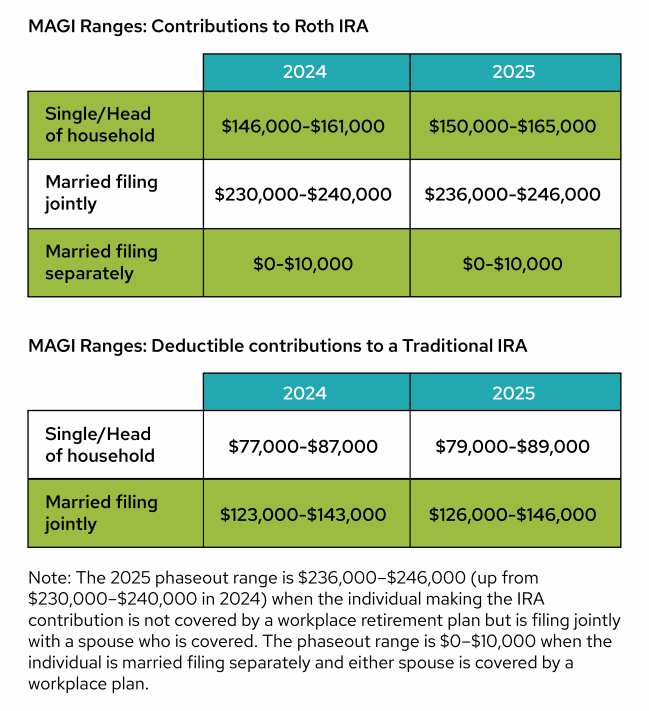
Below are the 2023 MAGI limits for the 2022 tax year. These numbers are used to screen applicants for Medicare Part D and Medicare Advantage plans.
- Single filer: $80,400
- Married filing jointly: $120,600
- Head of household: $68,900
- Individual with a spouse on a qualifying disability: $48,500
Note that if your MAGI exceeds these figures by 10% or more, you may be subject to a higher cost-sharing threshold (the “upper limit”) for Medicare Part D, which can increase monthly premiums, deductibles, and copayments.
How to Calculate Your MAGI
Step 1: Start with your Adjusted Gross Income (AGI) from your federal tax return.
Step 2: Add back the following to AGI:
- Tax‑exempt interest (e.g., municipal bonds)
- Foreign earned income and housing exclusions
- Alimony (for divorces finalized before 2019)
Step 3: Subtract the following deductions:
- Student loan interest deduction
- Tuition and fees deduction
- Retirement plan contributions that were excluded from AGI
The resulting figure is your MAGI. If you’re uncertain about any component, consider using a tax professional’s guidance or an online MAGI calculator.
Impact on Medicare Coverage Options
MAGI determines whether you qualify for:
- Premium Tax Credits (PTC): Reduce your monthly Part D or Medicare Advantage premiums.
- Low‑Income Subsidy (LIS): Lower premiums, deductibles, and copayments for Part D.
- Extra Help: Free or low‑cost prescription drug coverage if your MAGI falls below the Extra Help threshold ($20,300 for singles, $29,200 for families in 2022).
Failing to qualify can leave you with higher out‑of‑pocket costs, especially for high‑prescription‑drug users. Conversely, a lower MAGI can unlock significant savings, potentially reducing your Part D premium by $70–$140 a month.
Strategies to Manage Your MAGI
- Timing income: Defer bonuses or capital gains to the next tax year if possible.
- Maximize deductions: Contribute to a 401(k), traditional IRA, or HSA to lower AGI.
- Review tax brackets: Small adjustments can move you below a threshold, keeping your PTC or LIS intact.
- Consider a part‑time job: If you’re close to a limit, a short stint can push your MAGI into a lower bracket, especially for part‑time workers who can time earnings.
Annual Review is Key
Because MAGI is tied to your tax return, you should re‑calculate it each year after you receive your 1099s and W‑2s. A sudden change in employment, a sale of an asset, or a shift in marital status can move you into or out of subsidy eligibility. Using the CMS “Income Estimator” tool can quickly show how your current MAGI affects your Medicare costs.
FAQs About 2023 MAGI Limits
- Does Medicare income tax affect MAGI? No. The MAGI calculation starts with your AGI, which includes federal income taxes paid.
- Can I apply for Medicare after the enrollment period? You can enroll during a Special Enrollment Period (SEP) if you’re eligible for a change in coverage or income status, but you’ll still need to meet the MAGI thresholds.
- What if